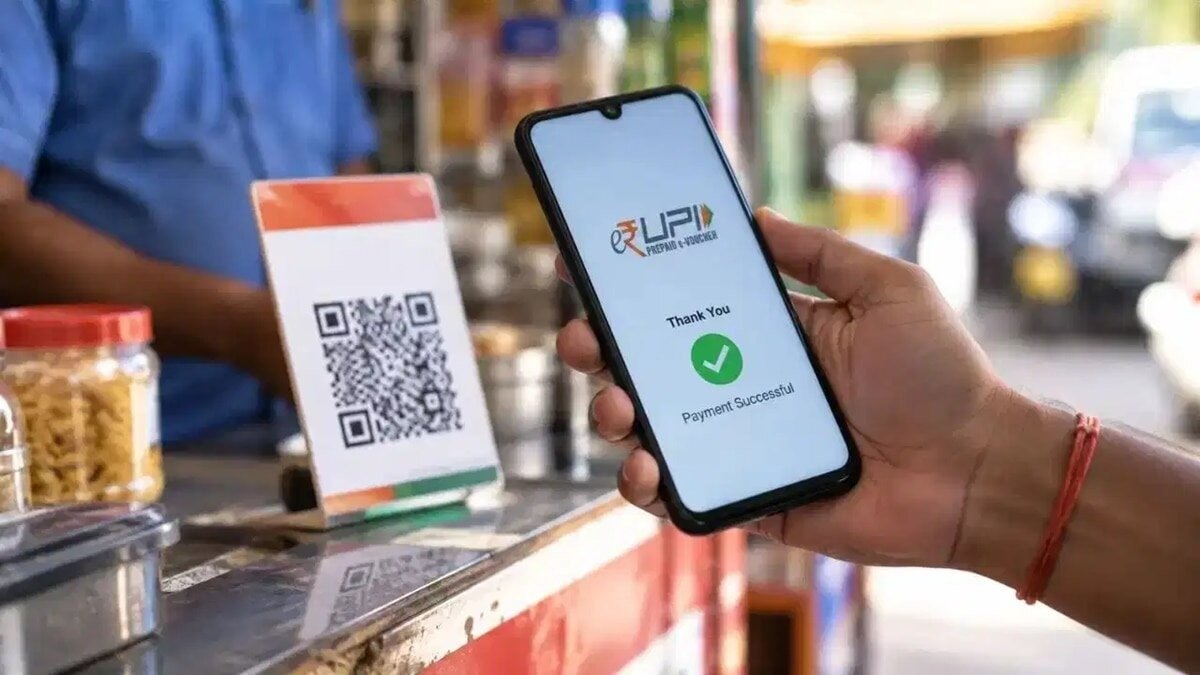
The UPI Steering Committee mounted the MDR at 0.40% for service provider transactions above Rs 2,000 on September 15, with the framework scheduled to take impact from October 15, 2026.
Nonetheless, the commerce our bodies have requested the federal government to roll again the cost.
How the report needs UPI charges break up
The report recommends an MDR of 0.06% for third-party utility suppliers (TPAPs), akin to PhonePe and Google Pay, in opposition to the 0.08% proposed by NPCI. It suggests retaining a 0.02% share for fee service suppliers (PSPs), that are principally banks.
The research argues that banks ought to quit their share of MDR income as a result of they already profit from the low rates of interest paid on present and financial savings account deposits, often known as CASA deposits.
Banks booked greater than Rs 4.85 lakh crore in internet curiosity margin by CASA deposits in FY26, which the report describes as “giant and disproportionate” compensation for offering fundamental banking providers.
“Banks earn substantial curiosity margins from the CASA depositors. They need to use the identical in the direction of operating and enhancing the UPI ecosystem and never depend on MDR income sharing from offline transactions,” the report mentioned.
It prompt that banks put aside about 3% of the funds successfully sacrificed by CASA depositors – round Rs 15,000 crore – to run and enhance UPI.
Banks ought to deal with UPI as a essential service
The report additionally referred to as on the RBI and the federal government to direct banks to make UPI a essential service for remaining within the banking enterprise, a lot as core banking programs (CBS) grew to become important to financial institution operations.
It questioned the reasonableness of a Rs 300 transaction cost cap for digital person-to-merchant funds of Rs 75,000 and above.
Such a cost, the report mentioned, “raises a significant query of reasonableness of fixing such a excessive cap as service cost”. It additionally cited RBI laws that require service expenses to be in keeping with the common value of offering the service.
The report advisable introducing a “digital fee charge” for on-line service provider transactions made when buying items or providers from e-commerce firms.
It additionally referred to as for a discount in bank card MDR.
The authors famous that many retailers coated by the UPI MDR framework already levy expenses on transactions above Rs 2,000 and settle for bank cards. Decrease bank card MDR, they argued, may tackle issues that bank card customers are inserting an unfair burden on UPI customers making person-to-merchant funds.