Mortgage charges will stay elevated above 7% by the top of subsequent yr, in keeping with the forecast of a prime housing economist with the Mortgage Bankers Affiliation.
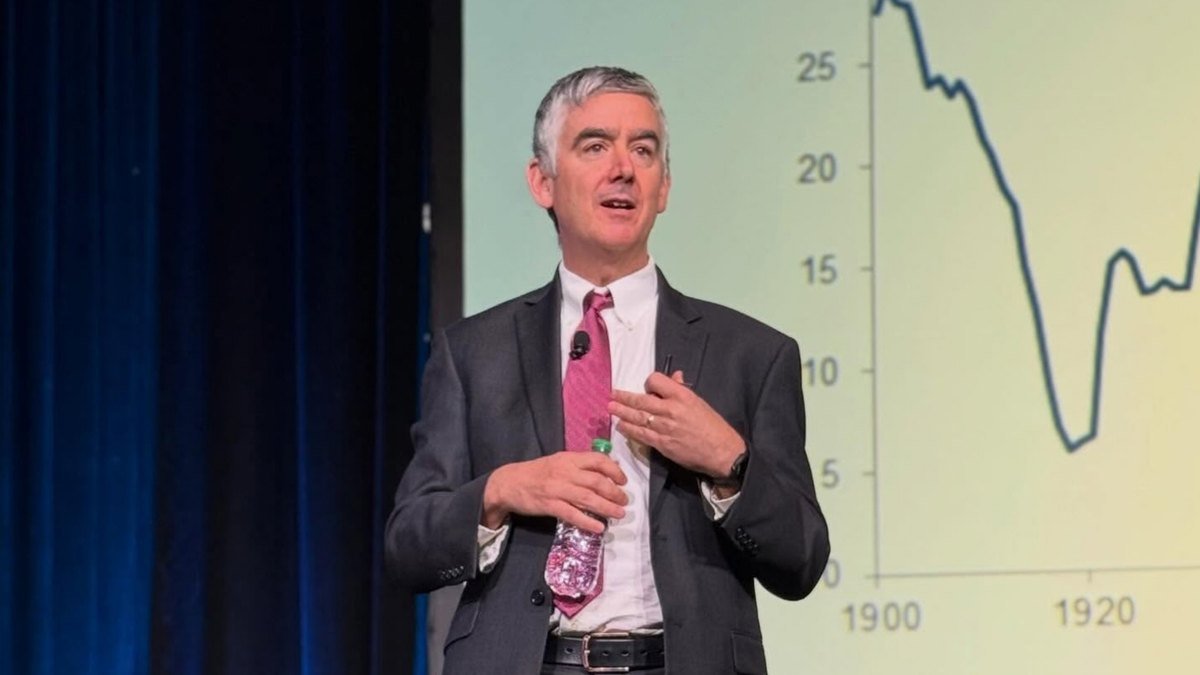
“Inflation is just too excessive, main central banks to boost short-term charges, whereas finances deficits and debt are unsustainably excessive, main bond traders to push up longer-term charges,” stated MBA Chief Economist Mike Fratantoni on the group’s annual convention on Sunday in Chicago.
Fratantoni expects that the 30-year mortgage fee will common 7.3% within the fourth quarter of 2026 and stay above 7% by 2027, pushed by elevated Treasury yields and extra restrictive central financial institution insurance policies.
As of final week, mortgage charges averaged 7.40%, a three-year excessive, in keeping with Freddie Mac. Charges have climbed sharply since late February, as the worldwide oil shock from President Donald Trump’s conflict with Iran ripples by the financial system, forcing the Federal Reserve to take motion on resurgent inflation.
Final month, the Fed hiked its benchmark rate of interest for the primary time in three years. Fratantoni says he expects two further quarter-point Fed hikes, one in December of this yr and one other within the first quarter of 2027. That may take the federal funds fee to a variety of 4.25% to 4.5%, a stage not seen since August 2025.
“Inflation stays properly above the Fed’s goal, and whereas the job market isn’t sturdy, we count on that the FOMC will proceed to focus intently on pushing inflation all the way down to its 2% inflation goal,” Fratantoni stated. The Fed makes use of greater rates of interest to struggle inflation, and decrease charges to stimulate the job market, in step with the central financial institution’s twin mandate of guaranteeing worth stability and full employment.
In current months, the Fed has been pressured to answer warning indicators from the bond market, the place the important thing 10-year Treasury yield touched 5.36% in intraday buying and selling final week, the best since 2002. The ten-year yield is a key benchmark for mortgage lenders, as a result of most 30-year mortgage are refinanced or closed out by a house sale inside roughly a decade.
Fratantoni forecasts that the 10-year Treasury yield will common 5.1% within the fourth quarter of 2026 and stay shut to five% by 2027.
The economist notes that there are a number of uncertainties related along with his forecast, with the potential for geopolitical or monetary market shocks to additional dampen client confidence.
Recession dangers stay elevated, with Fratantoni pegging the chance of a recession within the subsequent 12 months at round 35%.
“There are actual dangers that we get a big slowdown,” he stated. “The monetary markets are kind of priced to perfection alongside quite a lot of dimensions, and quite a lot of the [consumer] spending that’s occurring relies upon inventory market values being as excessive as they’re.”
MBA tasks fewer mortgage functions in 2027
By mortgage rely, MBA economists forecast complete mortgage origination quantity will lower by 5.6% to five.0 million loans in 2027, down from the 5.3 million loans anticipated in 2026.
Buy functions will lower barely from 2026 ranges, whereas refinance functions take an even bigger hit, in keeping with the forecast.
“As soon as we hit the 7% vary, you’ll be able to see the acquisition exercise dropping off a little bit bit extra considerably,” stated MBA Deputy Chief Economist Joel Kan, referring to the upward path of mortgage charges this yr.
Kan says the group’s survey information reveals homebuyers are more and more turning to adjustable-rate mortgages (ARMs), which provide a decrease introductory fee, however are riskier for patrons as a result of month-to-month funds on the loans might enhance considerably sooner or later.
“The patrons who’re nonetheless available in the market are more and more turning to ARM loans or paying factors to decrease their charges for the lifetime of the mortgage,” stated Kan. “The ARM share of functions averaged virtually 10% over the previous month and MBA forecasts that it’ll stay over 9% by 2027.”
Kan stated that within the coming years, slower pure inhabitants development and decrease immigration could contribute to decrease total demand for housing, relieving strain from a longstanding housing scarcity.
He argued that nationwide annual home-price development within the 2% vary in recent times signifies that the nationwide housing scarcity isn’t as extreme as beforehand estimated. Realtor.com economists have pegged the nationwide housing provide hole at greater than 4 million items.
“We count on declining ranges of latest development for each single-family and multifamily houses over the forecast interval,” stated Kan. “With fewer housing begins and comparatively flat residence gross sales anticipated, our forecast is for nationwide residence worth development to decelerate in 2027 earlier than steadily selecting up once more in 2028.”
In the meantime, Kan acknowledged a shortfall of inexpensive housing within the nation, and stated he hoped current curiosity in manufactured housing might assist fill the hole. This summer season, Congress handed the twenty first Century Street to Housing Act, which contained provisions to bolster manufactured housing.
“We have been underbuilding by way of entry stage items—, starter houses—for fairly a while, and do assume that with Street to Housing, there is a chance for manufactured houses,” he stated. Kan added there was a chance for manufactured housing to “step in, to sort of replenish and add to among the inexpensive housing inventory that is on the market.”
Get actual property information in your inbox