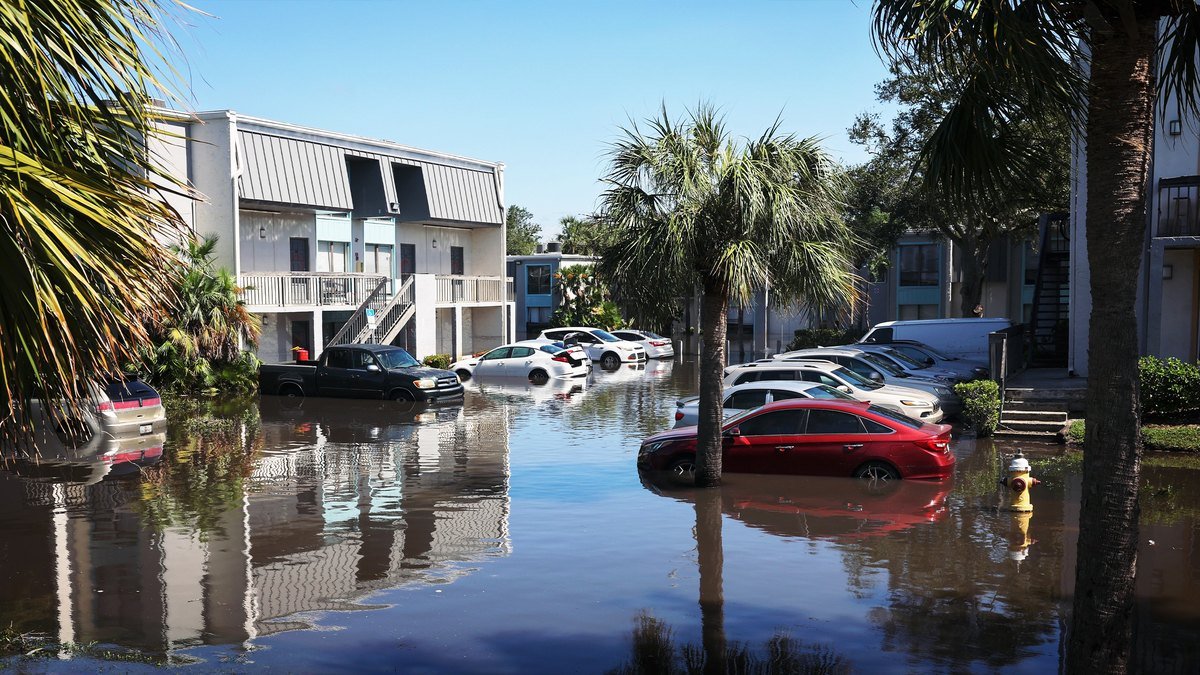
When a hurricane like Isaias strikes, affected householders might face 1000’s of {dollars} in restore prices and out-of-pocket bills.
In response to Angi, these may vary from $3,000 to $25,000, relying on the extent of the injury. And if your own home is situated in an HOA, it’s possible you’ll pay much more.
“After a hurricane, an HOA house owner might face two layers of restoration: injury to their very own residence and injury to frequent or shared property the affiliation maintains,” explains Donna DiMaggio Berger, shareholder at Becker and Poliakoff in Ft. Lauderdale.
How an HOA impacts householders after a hurricane
After a serious catastrophe like a hurricane, an HOA might have to restore frequent areas and infrastructure, tackle insurance coverage deductibles and uninsured losses, and restore important group providers.
If insurance coverage proceeds and present affiliation funds are inadequate, householders could possibly be charged a particular evaluation to fund their share of these prices.
Melanie Zimmerman, proprietor and actual property agent at MVP Chicago Actual Property in Chicago just lately labored with a consumer who lives in a Chicago space apartment and acquired a whopping particular evaluation of $7,400.
A part of the constructing’s roof had sustained wind and water injury. Whereas her private insurance coverage coverage coated the injury inside her unit, it didn’t pay for the constructing’s insurance coverage deductible.
“She was shocked by the evaluation, believing her common HOA dues would cowl bills like this. Let her story be a reminder that particular assessments may end up in different surprises and will not be coated by your fundamental HOA dues,” says Zimmerman.
If your own home shouldn’t be in an HOA, nevertheless, you carry the complete price of the injury, however have management over each choice concerned. You gained’t must navigate disputes over who’s answerable for a roof or wall, look ahead to board member choices, or pay assessments for group repairs.
Daybreak Bauman, CEO of Neighborhood Associations Institute in Falls Church, VA, factors out {that a} catastrophe doesn’t at all times imply an HOA house owner can pay extra.
“A well-managed affiliation may very well be higher ready as a result of it has been planning collectively for main repairs and emergencies via insurance coverage, reserve funding, upkeep, skilled administration, and catastrophe planning,” Bauman explains.
What to do to guard your self financially
When you stay in an HOA, learn your governing paperwork intently. Rise up to hurry on what’s your accountability vs. the affiliation’s accountability, significantly for roofs, home windows, doorways, landscaping, and different parts inclined to storm injury.
Then, overview its insurance coverage protection and your private house owner coverage so you realize what every coverage covers and the place gaps might exist.
“Ask your insurance coverage agent particularly about loss-assessment protection and whether or not the bounds are sufficient in your group’s potential publicity. Don’t assume your private protection will mechanically cowl each particular evaluation,” Berger explains.
Test your affiliation’s hurricane or named-storm deductible. In a big group, even a proportion deductible can translate into a considerable greenback quantity that in the end have to be funded by everybody who lives there.
Additionally, become involved in your HOA election and vote on all issues.
“Vote in your HOA election annually and assist candidates who stress sound fiscal planning and well-funded reserves. That’s what helps communities get better shortly and painlessly from most disasters,” says Berger.
Talking of reserves, Edward Susolik, president and trial lawyer at Callahan & Blaine in Irvine, CA, explains that the time to argue about them is on the annual assembly—not after a pure catastrophe strikes.
“As soon as a hurricane occurs, the board has the power to throw on assessments quick. And in case you by no means checked out that finances, you’ve acquired nothing to leverage,” provides Susolik.
It’s additionally necessary to keep up and doc your property’s pre-storm situation. Preventive measures can cut back injury and will assist protect obtainable insurance coverage rights.
If and when a catastrophe hits, doc injury promptly with date-stamped images and video. Then, notify your insurance coverage firm and protect receipts and different information regarding emergency work and repairs.
“Documentation could make the claims course of and restoration simpler,” says Bauman.