
The Query
My husband and I each have pupil loans ($48,000 for me and $52,000 for him). I utilized to maneuver to RAP final month after I bought a SAVE forbearance discover. We file collectively and our mixed AGI is round $118,000.
I used a calculator that confirmed one family cost of roughly $980. However once we every checked out our accounts, we’re every being billed near $980. That’s nearly $2,000 a month and we are able to’t afford that. Is that proper, or did one thing get processed incorrect? We’re contemplating submitting individually subsequent yr however I don’t know if that fixes it.
— Danielle
Welcome to the Friday mailbag, the place we take one reader query and reply it. Have one? Ship it to us — particulars on the backside.
The Brief Reply
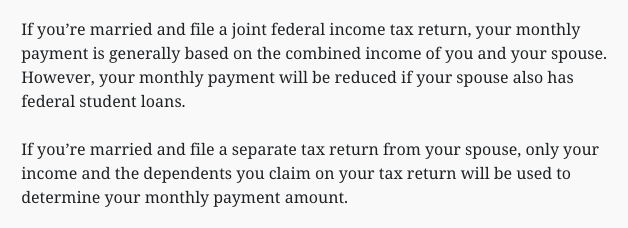
No, you shouldn’t be paying twice. Below RAP, a married couple submitting collectively will get one cost calculated on mixed revenue, and that cost is diminished when each spouses carry federal loans. Two full funds of $980 means one thing was processed incorrect, and you need to be roughly $983 a month between you. The $983 is then presupposed to be pro-rated throughout your loans. Since you’ve got 48% of the stability, your cost is meant to be $472 monthly. Your husband’s cost needs to be $511 monthly. The mixed cost is $983 monthly.
Right here’s the rules from StudentAid:
The Full Math Breakdown
At $118,000 in mixed AGI, you land in RAP’s high bracket: 10% of adjusted gross revenue, divided by 12. That’s $11,800 a yr, or $983 a month for the family. Should you declare dependents, subtract $50 per dependent from that determine. The RAP calculator will verify it along with your precise inputs.
That family cost then will get divided between the 2 of you based on how a lot of the mixed stability every carries. Your $48,000 is 48% of your $100,000 whole, so your share is about $472. Your husband’s $52,000 is 52%, so his is about $511. Add them collectively and also you’re again to $983.
You didn’t say when you had youngsters, however the $50/mo per dependent comes off the $983, not the person funds.
The full RAP cost guidelines stroll by means of the remainder of the mechanics, together with the curiosity waiver and the $50 month-to-month principal match.
Why This Is Complicated
Calculating your IDR cost as a married couple is complicated as a result of most calculators don’t do the pro-rating. It’s a must to use your mixed revenue, and understand the cost is your mixed cost.
It’s additionally necessary to understand that the one method this pro-rating occurs is that if each you and your partner are enrolled in the identical pupil mortgage compensation plan. We’re seeing a number of situations the place one partner is enrolled in compensation and the opposite one remains to be in forbearance, and the pro-rating is just not taking place.
We’re additionally seeing processing points. Since many of the cost calculations are dealt with by enterprise processing organizations (mainly outsourced), typically the knowledge doesn’t get processed appropriately. It’s actually necessary that each you and your partner are submitting IDR functions to go away the secure harbored forbearance, not simply one among you.
Does Submitting Taxes Individually Repair It?
It adjustments the maths, however if you do that, you’ll want to focus past your pupil mortgage cost and see the influence to your taxes. In case your incomes are roughly even (name it $59,000 every) submitting individually drops every of you into RAP’s 5% bracket. That’s about $246 a month apiece, or $492 for the family, towards $983 submitting collectively. On paper you save near $500 a month.
However if you file taxes individually, you just about all the time pay extra in taxes. Married submitting individually prices you the coed mortgage curiosity deduction outright, narrows or eliminates a number of credit, and pushes you into much less favorable tax brackets. For some {couples} that’s a couple of hundred {dollars} a yr and the commerce is apparent. For others (notably with kids or schooling credit in play) it wipes out all the pupil mortgage financial savings and extra. Our breakdown of the married submitting individually math reveals how one can run it each methods earlier than you commit.
They key resolution right here is whether or not your tax invoice will increase by $6,000 per yr or not (that’s $500/mo). Your taxes solely enhance by $4,000, you “win” by submitting separate. In the event that they enhance by $8,000, you lose by submitting separate.
You Could Be On The Improper Plan Anyway
At $118,000 mixed, you’re sitting proper the place RAP stops being the cheaper choice. RAP usually wins beneath roughly $80,000 to $90,000 in revenue. Above that, IBR’s discretionary-income formulation and shorter forgiveness timeline often pull forward. Our RAP vs. IBR comparability covers the place the crossover really falls.
Taking a look at your revenue (once more, not understanding your dependents), I see your cost being $728 mixed on IBR, when you’re each debtors after 2014. I might warning, although, that when you’re “outdated” debtors (that means loans earlier than 2014), then solely Outdated IBR is accessible and that cost is increased at $1,092 monthly mixed.
Relying in your objectives and historical past, the size of forgiveness timing additionally performs a job. IBR is 20 years for brand spanking new debtors, versus 30 years on RAP. Whereas it’s moot when you’re going for PSLF, when you don’t see yourselves repaying the mortgage earlier than that 20 yr mark, that is worthwhile.
What To Do This Week
- Pull each accounts on StudentAid and validate the billed quantity, the compensation plan title, and the date on every mortgage. You want the paper path earlier than you name.
- Affirm which plan every mortgage is definitely on. Popping out of SAVE forbearance, we’ve seen a number of odd issues.
- Escalate in writing, not by cellphone. Submit by means of your servicer’s safe message system so there’s a document, state that each spouses have federal loans and filed collectively, and ask particularly for the spousal mortgage debt adjustment to be utilized.
- File a grievance with the FSA Ombudsman if the servicer doesn’t right it inside a billing cycle. That escalation will get outcomes extra typically than a second cellphone name.
- Mannequin subsequent yr’s tax submitting standing within the spring if you file your taxes, as soon as your cost is right and you recognize what you’re really evaluating.
The place Individuals Get This Improper
The most typical dangerous recommendation on this query is that every partner owes a full cost based mostly on family revenue, so the one repair is submitting individually. That’s incorrect, and it could actually create tax points for {couples}.
The second mistake is assuming a servicer’s billed quantity is definitionally right. Via the SAVE wind-down and the RAP transition, debtors have been discovering errors at a charge no person needs to be comfy with. If the quantity doesn’t match the formulation, the quantity is what’s incorrect.
Ship Us Your Query
Bought a pupil mortgage, monetary help, or cash query you’ll be able to’t get a straight reply on? Ship it to us and we could reply it in a future Friday mailbag.
var gform;gform||(doc.addEventListener(“gform_main_scripts_loaded”,operate(){gform.scriptsLoaded=!0}),doc.addEventListener(“gform/theme/scripts_loaded”,operate(){gform.themeScriptsLoaded=!0}),window.addEventListener(“DOMContentLoaded”,operate(){gform.domLoaded=!0}),gform={domLoaded:!1,scriptsLoaded:!1,themeScriptsLoaded:!1,isFormEditor:()=>”operate”==typeof InitializeEditor,callIfLoaded:operate(o),initializeOnLoaded:operate(o){gform.callIfLoaded(o)||(doc.addEventListener(“gform_main_scripts_loaded”,()=>{gform.scriptsLoaded=!0,gform.callIfLoaded(o)}),doc.addEventListener(“gform/theme/scripts_loaded”,()=>{gform.themeScriptsLoaded=!0,gform.callIfLoaded(o)}),window.addEventListener(“DOMContentLoaded”,()=>{gform.domLoaded=!0,gform.callIfLoaded(o)}))},hooks:{motion:{},filter:{}},addAction:operate(o,r,e,t){gform.addHook(“motion”,o,r,e,t)},addFilter:operate(o,r,e,t){gform.addHook(“filter”,o,r,e,t)},doAction:operate(o){gform.doHook(“motion”,o,arguments)},applyFilters:operate(o){return gform.doHook(“filter”,o,arguments)},removeAction:operate(o,r){gform.removeHook(“motion”,o,r)},removeFilter:operate(o,r,e){gform.removeHook(“filter”,o,r,e)},addHook:operate(o,r,e,t,n){null==gform.hooks[o][r]&&(gform.hooks[o][r]=[]);var d=gform.hooks[o][r];null==n&&(n=r+”_”+d.size),gform.hooks[o][r].push({tag:n,callable:e,precedence:t=null==t?10:t})},doHook:operate(r,o,e){var t;if(e=Array.prototype.slice.name(e,1),null!=gform.hooks[r][o]&&((o=gform.hooks[r][o]).type(operate(o,r){return o.priority-r.precedence}),o.forEach(operate(o){“operate”!=typeof(t=o.callable)&&(t=window[t]),”motion”==r?t.apply(null,e):e[0]=t.apply(null,e)})),”filter”==r)return e[0]},removeHook:operate(o,r,t,n){var e;null!=gform.hooks[o][r]&&(e=(e=gform.hooks[o][r]).filter(operate(o,r,e)),gform.hooks[o][r]=e)}});
Reader Mailbag
Editor: Colin Graves
The submit We Each Have Scholar Loans. Does RAP Make Us Pay Twice? appeared first on The Faculty Investor.