What began as a dialog in a Washington, DC, steakhouse is now the legislation of the land.
However the architects of the largest housing invoice in 30 years fear about its implementation and the housing affordability topics it did not deal with.
It is now as much as cities throughout the nation to find out the success of the bipartisan, bicameral twenty first Century Street to Housing Act, lawmakers stated in the course of the U.S. Chamber of Commerce’s housing convention in DC on Monday. And that may play out because the 33,295 authorities our bodies with native zoning authority course of the handfuls of provisions within the invoice aimed toward making it simpler to construct and purchase a house.
“Lots of the communities are enthusiastic about it, however now we’re in that stage the place we have to write the laws,” stated Rep. Mike Flood (R-NE), who chairs the Housing and Insurance coverage Subcommittee. “So it is actually essential that everyone interact with the U.S. Division of Housing and City Growth. That is the stage we’re in proper now.”
A couple of modifications within the invoice have instant affect. However a overwhelming majority of the 125 implementation gadgets within the invoice fall upon HUD. A number of guidelines have to be formulated and applications developed. And the invoice carries no funding, a difficulty prone to come up within the authorities’s 2028 fiscal price range.
“For proper now, it is a good begin at getting folks to make use of their creativeness,” stated Rep. Emanuel Cleaver (D-MO), rating member of the subcommittee.
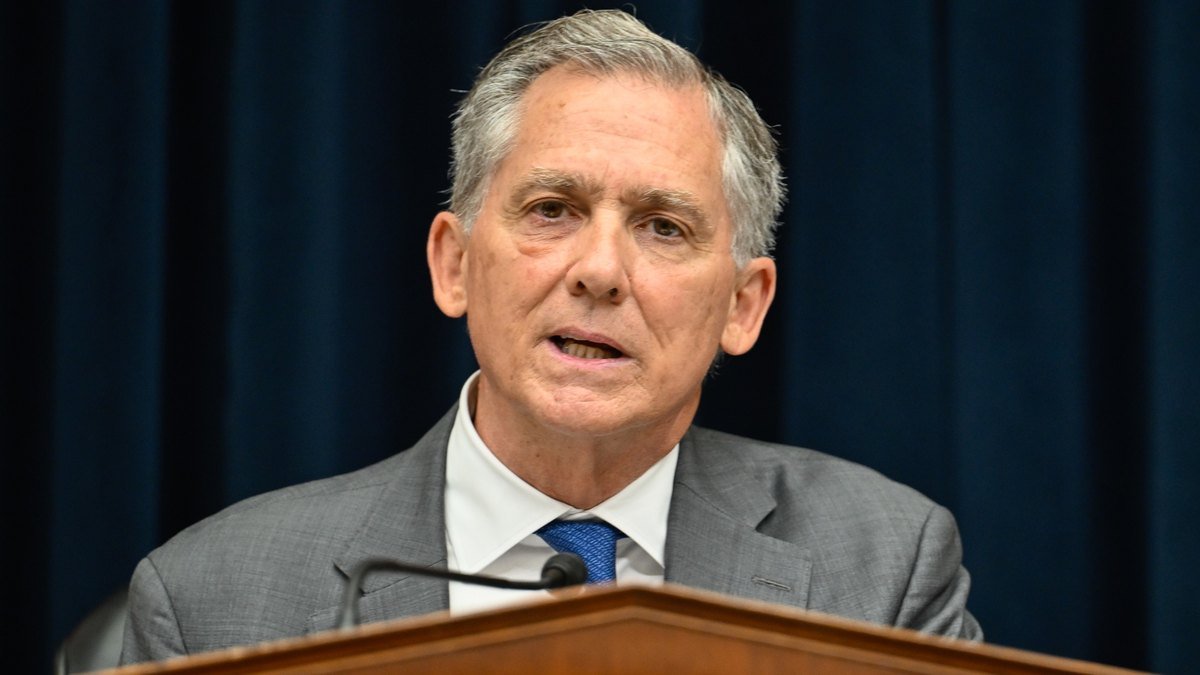
Home Monetary Companies Committee Chair Rep. French Hill (R-AR), the invoice’s sponsor, informed the Chamber the removing of the chassis mandate for manufactured housing, mixed with HUD laws that make it simpler to construct manufactured housing, gives “great value financial savings” for constructing extra housing in rural areas of Arkansas.
“They did a powerful job in working by way of this challenge about supply-side boundaries to better development, constructing higher provide for that simply easy fundamental Econ 100–kind challenge,” Hill stated.
Making an attempt to repair the issue on the demand facet, comparable to by way of lease management, “solely drives up costs extra,” Hill argued.
Flood stated the invoice pressured compromises from each events. He stated that began from the start of the dialogue on the invoice, at a now-shuttered DC restaurant referred to as The Prime Rib, the place they started to arrange which of the dozens of housing provisions from throughout Congress to start to include into the invoice.
“We simply dedicated to one another, let’s do that for all the suitable causes. I will not get every thing I need, you will not get every thing you need. However let’s get one thing carried out and see if we will promote it in Congress,” Flood recalled. “That partnership resulted in one of the best consequence you possibly can have.”
Native affect
Hill stated Congress has been housing reforms since he was a staffer within the Nineteen Eighties. However the system of incentives that encourages native governments to roll again laws can be key to the invoice. They’re paired with different modifications, such eradicating required Nationwide Environmental Coverage Act evaluations that save as much as $3,000 per unit. Lawmakers have additionally eyed different reforms.
“If you do not have good density, decrease improvement charges, and open a non-NIMBY kind of surroundings, you possibly can have your CDBG cash clipped,” Hill stated, referring to federal funding often called Group Growth Block Grants. “That is a superb incentive for states and cities to get their act collectively on native improvement guidelines.”
“The overwhelming majority of prices per unit are largely native,” Hill stated. “They’re choices taken by metropolis councils, county courts, and states. Each multifamily and single-family. So what we need to do was mannequin good habits by slicing regulatory crimson tape.”
In the meantime, Accelerator for America held an implementation listening to on the invoice Tuesday, the place Colin Higgins, govt director of its Nationwide Housing Disaster Activity Power, inspired native governments to not watch for the implementation of the invoice.
The invoice was “scaffolding” for applications that may come on-line in coming years, he stated.
Governments ought to create housing activity forces and set the stage to handle public land, manufactured housing, lending challenges, and allowing and environmental evaluations. It is best to start out now even earlier than funding comes.
“The feds have acted, however it will take a while,” Higgins stated.
When is the subsequent housing invoice?
Congress has expressed some enthusiasm for extra housing reform within the coming years. What precisely it does, although, depends upon whom you ask.
“The one factor I believe we did not get—that we would have liked right here—was the outright elimination of making use of ‘Construct America Purchase America’ to housing,” Flood informed the convention. That provision provides scrutiny to constructing supplies, aiming to encourage builders to supply extra supplies in the US.
However, Flood stated, whereas he helps the legislation, it should not apply to homebuilding.
“It has added prices on a stage that may shock you,” he stated. Flood additionally referred to as for housing insurance coverage reform, however admitted it is prone to require “complicated options.”
“There’s much more to do,” Hill stated. “We have to proceed this supply-side deregulatory push, we have to maintain HUD accountable. One of many least accountable businesses within the authorities.”
Hill listed some ongoing Republican priorities that Congress may deal with if they maintain the bulk after the 2026 midterms. That features reforms to Fannie Mae and Freddie Mac. He additionally echoed HUD’s continued criticism of “Housing First” homelessness applications.
And he wished to see motion on the Fed’s proposed BASEL III reforms aimed to encourage extra banks to finance mortgages and development loans.
“That ought to take steps to encourage the big banks to take part within the secondary marketplace for housing,” Hill stated. “I believe Dodd-Frank went too far on this level. Basically, by the capital requirements for a development mortgage, pushed a whole lot of the most important banks out of that enterprise. It additionally restricted mortgage servicing rights by the big monetary establishments. Each of these issues, on the margin, increase the price of liquidity for housing.”
Cleaver took the other tack, arguing extra bipartisanship will craft the subsequent housing invoice.
“You may’t sting and make honey on the similar time,” Cleaver stated. “You have obtained to choose. Are you going to be a stinger or are you going to make honey? The honey is laws. The sting is all of the bickering and combating now we have an excessive amount of of proper now.”
Get actual property information in your inbox