Key Factors
- The 2027 restrict for 401(okay), 403(b), 457 and Thrift Financial savings Plan contributions rises $1,000 to $25,500, with catch-up contributions of $8,500 at age 50 and $11,750 at ages 60 to 63.
- IRA contributions keep capped at $7,500 for 2027 with a $1,100 catch-up, however the Roth IRA earnings phase-out climbs to $158,000 to $173,000 for single filers.
- These limits apply to cash you contribute in 2027, so elevate your payroll election throughout open enrollment or earlier than your first January paycheck.
The IRS introduced on November 12, 2026 that employees can put as much as $25,500 right into a 401(okay) in 2027, up from $24,500 this yr. The identical restrict covers 403(b) plans, authorities 457 plans and the federal Thrift Financial savings Plan.
The IRS announcement leaves the IRA restrict at $7,500, the identical as 2026. You possibly can evaluate each determine with our 401(okay) contribution and earnings limits web page.
The total tables sit in IRS Discover 2026-66 (PDF File). Complete worker and employer contributions can attain $75,000, and the wage threshold for obligatory Roth catch-ups rises to $155,000.
These adjustments come every week after the IRS launched the 2027 tax brackets and commonplace deduction.
| Account Or Restrict | 2026 | 2027 |
|---|---|---|
| 401(okay), 403(b), 457 And TSP Worker Restrict | $24,500 | $25,500 |
| Catch-Up Contribution, Age 50 And Older | $8,000 | $8,500 |
| Catch-Up Contribution, Ages 60 To 63 | $11,250 | $11,750 |
| Complete Worker And Employer Contributions | $72,000 | $75,000 |
| Conventional And Roth IRA | $7,500 | $7,500 |
| IRA Catch-Up, Age 50 And Older | $1,100 | $1,100 |
| SIMPLE IRA And SIMPLE 401(okay) | $17,000 | $17,500 |
| SIMPLE Larger Restrict At Sure Small Employers | $18,100 | $19,100 |
| SIMPLE Catch-Up, Age 50 And Older | $4,000 | $4,000 |
| SIMPLE Catch-Up, Ages 60 To 63 | $5,250 | $5,250 |
| SEP IRA | $72,000 | $75,000 |
| HSA, Self-Solely Or Household Protection | $4,400 / $8,750 | $4,500 / $9,000 |
| Roth Catch-Up Wage Threshold | $150,000 | $155,000 |
Would you want to save lots of this?
What Are The 2027 401(okay) Contribution Limits?
The 2027 worker contribution restrict for 401(okay), 403(b), governmental 457 plans and the TSP is $25,500. Staff 50 and older can add an $8,500 catch-up contribution, for a complete of $34,000. Anybody turning 60, 61, 62 or 63 in 2027 will get a better $11,750 catch-up if the plan affords catch-ups, for a complete of $37,250. The $25,500 restrict is per individual throughout each 401(okay) and 403(b) you contribute to. Governmental 457(b) plans carry their very own separate restrict, as our comparability of 403(b) and 457 plans explains.
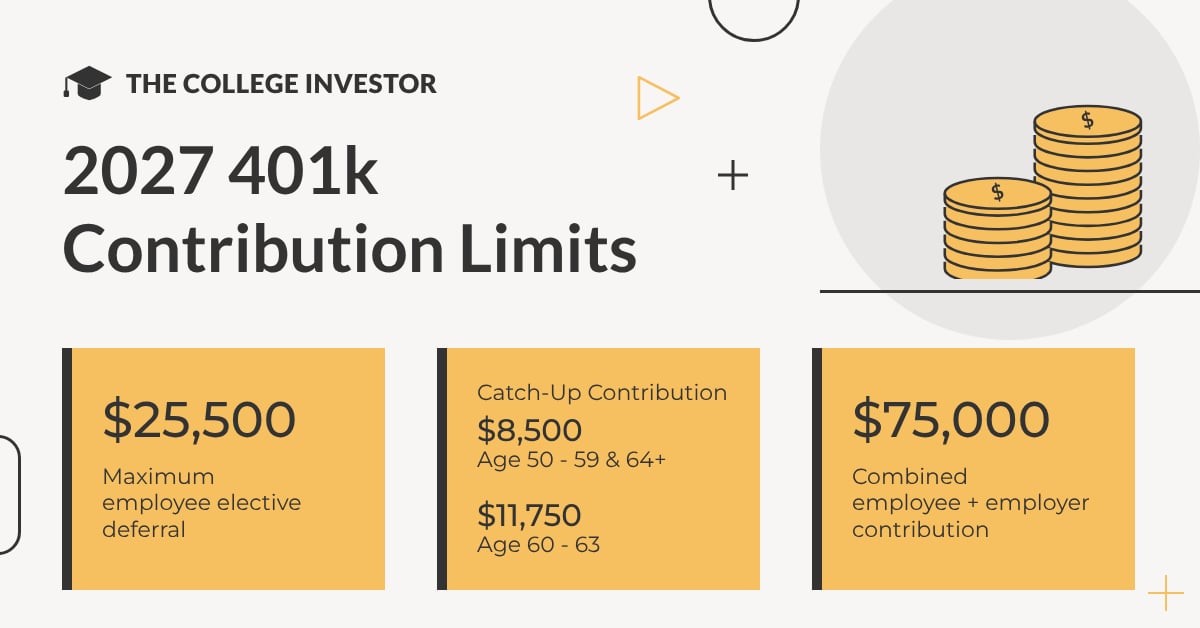
Complete contributions from you and your employer, together with the match and any revenue sharing, can attain $75,000 in 2027, up $3,000. Catch-up contributions sit on prime of that cap. The upper ceiling issues most for self-employed savers with a solo 401(okay) and for employees who use after-tax cash for a mega backdoor Roth.
| Age In 2027 | 401(okay) Worker Restrict | IRA Restrict | Mixed |
|---|---|---|---|
| Underneath 50 | $25,500 | $7,500 | $33,000 |
| 50 To 59, Or 64 And Older | $34,000 | $8,600 | $42,600 |
| 60 To 63 | $37,250 | $8,600 | $45,850 |
Who Should Make Roth Catch-Up Contributions In 2027?
Staff who earned greater than $155,000 in FICA wages from their employer in 2026 should make any 2027 catch-up contributions as Roth contributions. The edge rose from $150,000. That SECURE 2.0 requirement first utilized in 2026, and our protection of the Roth catch-up rule for prime earners explains who it hits.
Roth catch-ups go in after tax, in order that they not decrease your taxable earnings that yr. In case your plan doesn’t provide a Roth choice, employees above the edge can’t make catch-up contributions in any respect. Ask HR now whether or not your plan affords a Roth 401(okay) earlier than you set your 2027 election.
What Are The 2027 IRA Contribution Limits?
The 2027 IRA contribution restrict is $7,500, unchanged from 2026. Savers 50 and older can add $1,100, for $8,600 in complete. The restrict applies throughout all your conventional and Roth IRAs mixed, as our IRA contribution and earnings limits web page explains.
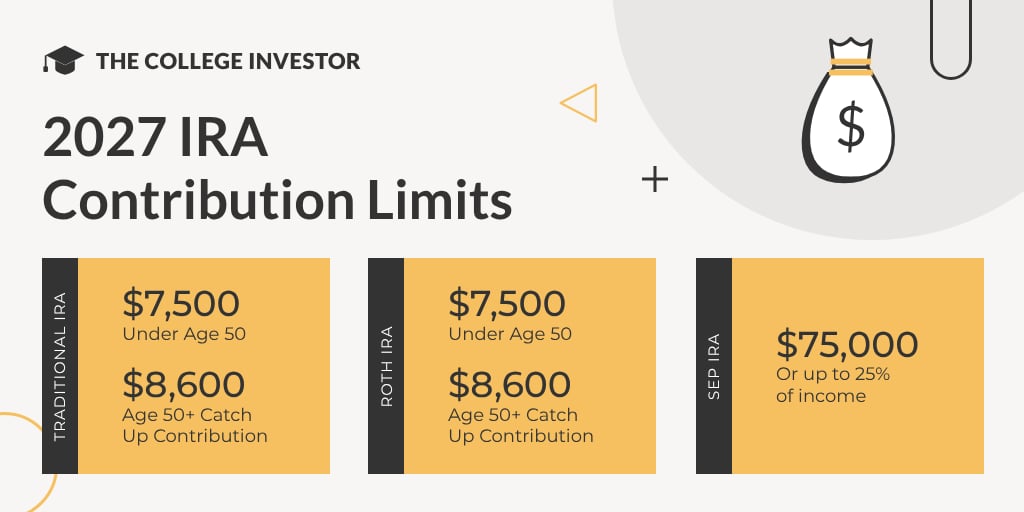
The IRA restrict solely strikes in $500 steps, so it stays flat till inflation pushes it over the subsequent step. A non-working partner can fund a spousal IRA as much as the identical restrict, so long as the couple recordsdata collectively and has sufficient earned earnings to cowl each contributions.
2027 Roth IRA And Conventional IRA Earnings Limits
Single filers and heads of family could make a full Roth IRA contribution with modified AGI beneath $158,000 in 2027, and eligibility ends at $173,000. Married {couples} submitting collectively section out between $250,000 and $260,000. Savers above these ranges can nonetheless use a backdoor Roth IRA.
| Filer | 2026 Vary | 2027 Vary |
|---|---|---|
| Roth IRA: Single Or Head Of Family | $153,000 – $168,000 | $158,000 – $173,000 |
| Roth IRA: Married Submitting Collectively | $242,000 – $252,000 | $250,000 – $260,000 |
| Roth IRA: Married Submitting Individually | $0 – $10,000 | $0 – $10,000 |
| Conventional IRA Deduction: Single, Lined At Work | $81,000 – $91,000 | $83,000 – $93,000 |
| Conventional IRA Deduction: Joint, Contributor Lined | $129,000 – $149,000 | $133,000 – $153,000 |
| Conventional IRA Deduction: Joint, Solely Partner Lined | $242,000 – $252,000 | $250,000 – $260,000 |
| Conventional IRA Deduction: Separate, Lined At Work | $0 – $10,000 | $0 – $10,000 |
The normal IRA deduction phase-out solely applies whenever you or your partner has a retirement plan at work. A single filer lined at work loses the deduction between $83,000 and $93,000 of modified AGI. Our Roth vs. conventional IRA choice tree helps you choose between the 2.
How Do SIMPLE IRA, SEP IRA And HSA Limits Change In 2027?
The SIMPLE IRA restrict rises to $17,500 from $17,000, and sure small employers can provide a better $19,100 restrict. SIMPLE catch-ups keep at $4,000 for many employees 50 and older and $5,250 at ages 60 to 63. SEP IRA contributions can attain 25% of compensation, capped at $75,000, per our SEP IRA contribution limits web page.
HSA limits for 2027 had been set earlier this yr at $4,500 for self-only protection and $9,000 for household protection, as we reported when the 2027 HSA limits got here out. Savers 55 and older can add $1,000. Many savers deal with an HSA as a second retirement account.
What Occurs To The Saver’s Credit score In 2027?
Beginning in 2027, the Saver’s Credit score not applies to 401(okay) or IRA contributions. The brand new $1,000 Saver’s Match replaces it for these contributions, with the federal match deposited into the saver’s retirement account. A footnote in Discover 2026-66 confirms the Saver’s Credit score survives just for contributions to ABLE accounts.
For ABLE contributions, the credit score’s prime earnings restrict rises to $83,000 for married {couples} submitting collectively, $62,250 for heads of family and $41,500 for single filers. Decrease-income savers who contribute to a 401(okay) or IRA ought to look ahead to the match after they file their 2027 return, and we monitor it alongside the opposite greatest tax breaks households can use.
How Do The 2027 Limits Have an effect on Scholar Mortgage Funds?
Conventional 401(okay) contributions decrease your adjusted gross earnings, and the Reimbursement Help Plan units your fee from AGI. That makes the brand new $25,500 restrict one of many few authorized methods to chop a RAP scholar mortgage fee with out incomes much less. RAP costs 1% to 10% of complete AGI, based mostly on the $10,000 bracket your earnings lands in.
We ran a single borrower with no dependents and a $90,000 wage by means of the 2027 guidelines, utilizing the usual deduction and no different earnings. With no 401(okay) contributions, the RAP fee is $600 a month. Maxing the 401(okay) at $25,500 drops AGI to $64,500 and the fee to $322.50. Federal earnings tax falls $5,198 below the 2027 federal tax brackets.
| Single Borrower, $90,000 Wage | No 401(okay) | $25,500 To 401(okay) |
|---|---|---|
| Adjusted Gross Earnings | $90,000 | $64,500 |
| RAP Charge | 8% | 6% |
| Month-to-month RAP Fee | $600 | $322.50 |
| Federal Earnings Tax | $10,690 | $5,492 |
| Yearly Financial savings | — | $8,528 |
RAP’s brackets create cliffs price planning round. The identical borrower contributing $9,000 lands at $81,000 of AGI and nonetheless pays 8%, or $540 a month. Contributing $10,000 drops AGI to $80,000 and the speed to 7%, which cuts the fee to $466.67. That further $1,000 saves $880 a yr in funds, so take a look at your election in our RAP calculator first.
Your RAP fee is mostly based mostly on the AGI out of your most up-to-date federal tax return, so 2027 contributions present up whenever you recertify utilizing your 2027 return. Debtors whose employers provide a scholar mortgage 401(okay) match may acquire retirement matching {dollars} on their scholar mortgage funds.
What Ought to You Do Now?
- Elevate your 401(okay) election for January. Maxing out at $25,500 takes $980.77 per biweekly paycheck, and our order of operations for retirement saving reveals the place the 401(okay) suits.
- End your 2026 IRA contribution. You’ve gotten till April 15, 2027 to fund a 2026 IRA on the 2026 limits, and our greatest IRA accounts listing can assist you open one.
- Test your Roth IRA eligibility. Examine your anticipated 2027 modified AGI with the brand new ranges, and learn to calculate your adjusted gross earnings in the event you aren’t certain.
- Ask about Roth catch-ups in the event you earned over $155,000. Your plan wants a Roth 401(okay) choice so that you can hold making catch-up contributions.
- Run the RAP math earlier than open enrollment ends. Our listing of pre-tax strikes that decrease your scholar mortgage fee covers the 401(okay), HSA and dependent care FSA collectively.
The publish 2027 401(okay) And IRA Contribution Limits From The IRS appeared first on The School Investor.