Earlier this yr, I used to be sick for 2 weeks. Sadly, I’ve had bronchial asthma since I used to be a child. So when a respiratory sickness hits, I are inclined to cough and undergo longer than the typical particular person.
Throughout COVID, my bronchial asthma flared up extra usually, doubtless as a result of stress of getting a child throughout a pandemic.
It’s the kind of respiratory the place you’re annoyingly acutely aware of each breath. You may by no means fairly fill your lungs to 100%. In my case, it felt extra like 75%.
On Wednesday, August 12, nonetheless sick, I made a decision to maintain a beforehand scheduled consulting name with an FS reader. I had booked it assuming I’d be higher by then. I wasn’t.
By the tip of our 1 hour, 15 minute session, the place I spent about 80% of the time speaking, I used to be worn out. My power had dropped to perhaps 30%. Once you’re speaking nonstop, you’re not respiratory deeply or frequently. I felt like I used to be slowly suffocating whereas discussing their asset allocation.
The decision jogged my memory of the various days I felt bodily drained speaking to shoppers throughout my 13 years in finance. As my tasks and stress grew, I finally hit a breaking level. I’d fairly earn nothing and be free and wholesome than hold grinding myself down.
Then My Again Gave Out
Simply the opposite day, I couldn’t bend down to choose one thing up with no sharp ache capturing by way of my backbone. I nearly collapsed.
The final time I felt ache this unhealthy was in 2023. I had spent an hour sitting on the bottom signing copies of Purchase This Not That for readers who donated to victims of the Maui fires. My dad is from Hawaii, and seeing 1000’s of lives upended in a single day weighed on me. The Monetary Samurai neighborhood ended up donating about $48,000. However when the signing was over, I couldn’t get up and I known as my spouse for assist.
My principle is that these episodes are triggered by a mixture of extended stress and me forgetting I’m not 25 anymore.
Overdoing Bodily Workouts
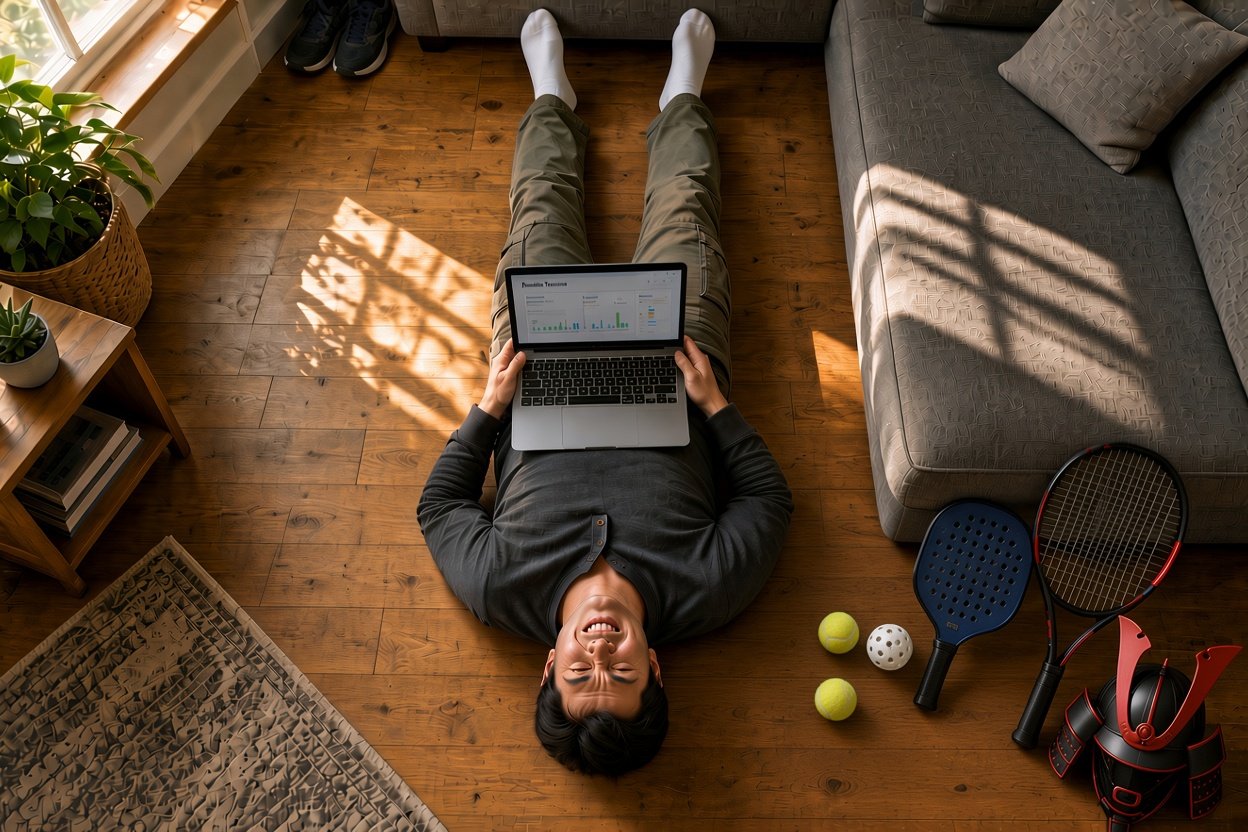
This time, I clearly forgot. On Sunday, I performed two hours of 4.5-level pickleball, then taught my youngsters for one more hour. On Monday, I performed 1.5 hours of intense tennis with loads of serving. Then on Tuesday, a number of dads in our dad bod problem shared their gymnasium Private Information, so naturally I went for private data too. As an alternative of my traditional three units of 10-12 reps, I did 5 units with progressive loading.
Wednesday morning, my again was already grumbling. So after all I went on a hilly 30-minute stroll at 7:05am earlier than breakfast and the college drop off. Strolling downhill to highschool, the ache returned. By the point I bought dwelling, I may not stroll usually.
If I nonetheless had a day job, there’s no method I may have gone into the workplace. And if my bronchial asthma flared up on the identical time, I couldn’t converse to shoppers for greater than an hour or two a day.
Not with the ability to present for my household can be a horrible factor.
What A Unhealthy Again And Struggling Lungs Taught Me
These two episodes compelled me to confront a couple of uncomfortable truths:
- A bodily or psychological incapacity can finish your profession whenever you least anticipate it. Don’t take your well being without any consideration.
- Use your well being whilst you nonetheless have it. Earn, construct, and play exhausting throughout your healthiest years, as a result of they’re finite. You gained’t have the ability to spend your cash when previous.
- Diversify the way you earn. If one earnings stream disappears, one other must take its place.
- Don’t commit the second largest mistake in private finance: extrapolating your earnings into the longer term as if it’s going to at all times go up.
Some folks image incapacity as a dramatic automotive accident or a fall off a ladder. Actuality is way extra boring. Unintended accidents make up solely about 9% to 12% of long-term incapacity claims, whereas musculoskeletal issues like again and joint ache are the main trigger, at 26% to 33% of claims.
In keeping with the Social Safety Administration (SSA), roughly one in 4 20-year-olds will probably be out of labor for no less than a yr due to a disabling situation earlier than reaching regular retirement age. That’s one quarter of all 20-year-olds, not simply these in high-risk occupations.
In different phrases, the factor that takes you out of the workforce most likely gained’t be a skydiving mishap. It’ll be your again after one too many weightlifting makes an attempt.
Brief-Time period Incapacity vs. Lengthy-Time period Incapacity
Earlier than moving into what to do, it’s price understanding the 2 foremost kinds of incapacity protection. They work very otherwise.
Brief-term incapacity (STD) covers you for a short lived incapability to work, like recovering from surgical procedure, a nasty again, or a severe sickness. Advantages usually change round 50% to 70% of your earnings and final wherever from a couple of weeks to about six months. The ready interval, known as the elimination interval, is normally brief, usually one to 2 weeks.
Many employers present short-term incapacity as a profit. A handful of states additionally run their very own packages, together with California (SDI), New York, New Jersey, Rhode Island, and Hawaii (TDI). When you’re self-employed, you most likely don’t have anything until you acquire it your self.
Lengthy-term incapacity (LTD) kicks in when a incapacity lasts longer, normally after a 90-day elimination interval. It usually replaces about 60% of your earnings and will pay for a set variety of years or till age 65. That is the protection that truly protects your loved ones’s monetary future. Brief-term incapacity is a velocity bump. Lengthy-term incapacity is a automotive crash.
Two particulars matter loads:
- Personal-occupation vs. any-occupation. An own-occupation coverage pays in case you can’t do your job. An any-occupation coverage solely pays in case you can’t do any job you’re fairly fitted to. A surgeon who loses positive motor expertise may nonetheless educate, so an any-occupation coverage might not pay a dime. Learn the positive print: many long-term incapacity insurance policies use the own-occupation definition for less than the primary 24 to 48 months, then swap to the stricter any-occupation definition.
- Taxes. In case your employer pays the premiums, advantages are usually taxable. When you pay premiums with after-tax {dollars}, advantages are usually tax-free. That 60% alternative price can rapidly really feel like 45%.
And no, don’t depend on Social Safety Incapacity Insurance coverage to save lots of you. SSDI is tough to qualify for, has a five-month ready interval, and the month-to-month profit is modest. It’s a flooring, not a plan.
5 Issues To Do To Defend Your Funds From A Incapacity
1) Get Lengthy-Time period Incapacity Insurance coverage, And Test The Effective Print
In case you have a job with advantages, log into your HR portal immediately and take a look at your LTD protection. Many group insurance policies cap month-to-month advantages, which implies excessive earners might solely be changing a fraction of their earnings.
If there’s a niche, purchase a supplemental particular person coverage, ideally with an own-occupation rider. It’s transportable, so it stays with you in case you go away your job. When you’re self-employed like me, particular person LTD is the one protection you’ll have. Get quotes whilst you’re younger and wholesome, as a result of pre-existing situations get excluded or priced up later.
2) Construct An Emergency Fund That Covers The Ready Interval
Even with nice protection, there’s a niche. Brief-term incapacity would possibly make you wait per week or two, and long-term incapacity normally makes you wait 90 days. In the meantime, your mortgage, tuition, and Costco runs don’t pause.
Hold no less than six months of dwelling bills in money or Treasury payments. In case you have youngsters, a single earnings family, or are self-employed, intention for 12 months. When you’re questioning the place the road is between prudent and paranoid, right here’s my tackle how a lot financial savings is an excessive amount of. The emergency fund is your bridge from wholesome to lined.
3) Construct A number of Engines Of Earnings With Aspect Hustles
A single earnings stream is a single level of failure. If that engine stalls, the entire aircraft goes down. Your objective is to construct a jet with no less than 4 engines, so you possibly can lose one and nonetheless land safely.
The perfect time to start out a aspect hustle is whilst you nonetheless have a gradual paycheck and good well being. You get to experiment with out strain, and if it fails, you continue to eat.
I began Monetary Samurai in July 2009 whereas working full-time in finance. I’d get up early and write earlier than work, then publish once more on weekends. For 3 years, it made little or no cash. However by the point I left Company America in 2012, the positioning had turn out to be an actual second engine alongside about $80,000 a yr in passive funding earnings.
With out that second engine, I by no means would have had the braveness to barter my method out.
Diversify Your Aspect Hustles Too
Right here’s the important thing for incapacity planning: prioritize aspect hustles that don’t require your physique to point out up. Driving for Uber or teaching tennis stops the second your again offers out. Writing, a weblog, a YouTube channel, a web-based course, or a self-published e-book can hold paying whilst you’re flat in your again.
When you want concepts, my spouse put collectively an inventory of the 20 finest aspect hustle concepts to make extra cash. If you wish to go the net route, right here’s the best way to begin a weblog and construct your personal platform. I’m biased, however proudly owning your personal nook of the web is the reward that retains on giving.
One engine is a job. Two engines is a cushion. 4 or extra engines is freedom.
4) Save Aggressively Whereas You’re Wholesome
Your peak incomes years are additionally, conveniently, your peak well being years. Don’t assume your earnings will hold climbing eternally. Assume it may drop to zero tomorrow, then save as if that’s true.
Associated: Reaching FI With A Visible Impairment
I saved over 50% of my after-tax earnings beginning with my first job out of school as a result of I knew I couldn’t final a lifetime working 70+ hours per week. I didn’t know my lungs and again would finally be a part of the protest, however the logic held up.
Entrance-load your financial savings. Max out your 401(ok) and IRA, and make investments the surplus in a taxable brokerage account. Pay down excessive fastened prices the place you possibly can.
The decrease your required month-to-month bills, the much less earnings alternative you want if catastrophe strikes. A paid-off home is among the finest incapacity insurance coverage coverage no one talks about.
5) Deal with Your Well being Like Your Most Helpful Asset
Your capability to earn over the following 20 to 30 years is probably going price tens of millions. But we handle our portfolios extra fastidiously than our our bodies.
Get annual checkups. However lock down a life insurance coverage coverage earlier than you see a health care provider for one thing extra. Handle your stress earlier than it manages you. Heat up, settle down, and cease attempting to beat the opposite dads’ PRs after a weekend of nonstop racquet sports activities. Ask me how I do know.
Whilst you’re at it, get your paperwork so as. A will, a sturdy energy of legal professional, and a healthcare directive are the fundamentals. But when anybody is determined by your earnings, time period life insurance coverage is a very powerful piece. A incapacity takes away your capability to earn for some time. Demise takes it away for good.
The irony is that the well being issues that make you are concerned about incapacity additionally make life insurance coverage dearer, or more durable to get. Lock in protection whilst you’re nonetheless wholesome sufficient to qualify. I’d evaluate time period life quotes on Policygenius, which helps you to see costs from a number of prime insurers in a single place.
Don’t Take Your Well being For Granted
The scary factor about incapacity is that it hardly ever pronounces itself. Someday you’re serving aces and going for gymnasium PRs. The subsequent, you possibly can’t stroll your youngsters to highschool.
Being unable to breathe usually or stroll for a couple of days made me understand how fragile every little thing is. When you’re the supplier for your loved ones, that fragility is your accountability to plan for.
So examine your incapacity protection this week. Construct your money buffer. Begin a aspect hustle that doesn’t rely in your physique exhibiting up. And for goodness sake, stretch.
Have you ever ever been unable to work for an prolonged interval as a result of an sickness or harm? Are you aware whether or not your employer’s long-term incapacity coverage is own-occupation or any-occupation, and when it switches? What number of engines of earnings do you will have immediately, and which might hold working in case you couldn’t get off the bed? Have you ever purchased supplemental incapacity insurance coverage, or do you suppose it’s a waste of cash? And what aspect hustle would you begin in case your foremost earnings disappeared tomorrow?
To get new posts in your inbox as quickly as they’re revealed, ad-free for the primary few hours, join the free Monetary Samurai publication right here. Be part of 60,000+ readers constructing wealth and breaking free sooner.
Construct Your Engines Whereas You Nonetheless Can
This put up is about how rapidly your capability to earn can disappear. The perfect protection is constructing wealth and a number of earnings streams throughout your healthiest years, earlier than your again and lungs begin submitting complaints.
That’s precisely what I lay out in my USA Right this moment bestseller, Millionaire Milestones: Easy Steps To Seven Figures. I’ve distilled 30 years of expertise finding out, working in, and writing about private finance right into a roadmap for reaching $1 million and past, whilst you nonetheless have the power to take pleasure in it.
Get a duplicate immediately. Your future self, presumably mendacity flat on the ground with a nasty again, will thanks.