The settlements had been accomplished. The insurer’s permission wasn’t
What occurred: James River Insurance coverage alleges Mueller Industries settled faulty press-fitting claims at 140 websites throughout 24 states with out ever asking permission
Who’s concerned: James River Insurance coverage (insurer) and Mueller Industries (producer, NYSE: MLI)
What’s at stake: Reimbursement for dozens of settlements Mueller entered into unilaterally, with James River in search of a declaration it owes nothing underneath each a major legal responsibility coverage and an extra coverage
Why it issues: The case checks what occurs when an insured settles product claims at scale with out looping in its provider – and whether or not consent-to-settle provisions can void protection completely
The place it stands: Grievance filed October 22, 2026
100 and forty areas. Twenty-four states. Dozens of settlements. And, based on the insurer, not a single request for permission.
James River Insurance coverage Firm has taken Mueller Industries to federal court docket in Memphis, asking a decide to declare it owes nothing – not underneath the first legal responsibility coverage, not underneath the surplus coverage – for settlements Mueller reached over faulty press fittings at properties throughout the nation. Mueller Industries (NYSE: MLI) is a publicly traded piping and industrial merchandise producer headquartered in Collierville, Tennessee.
The fittings and the fallout
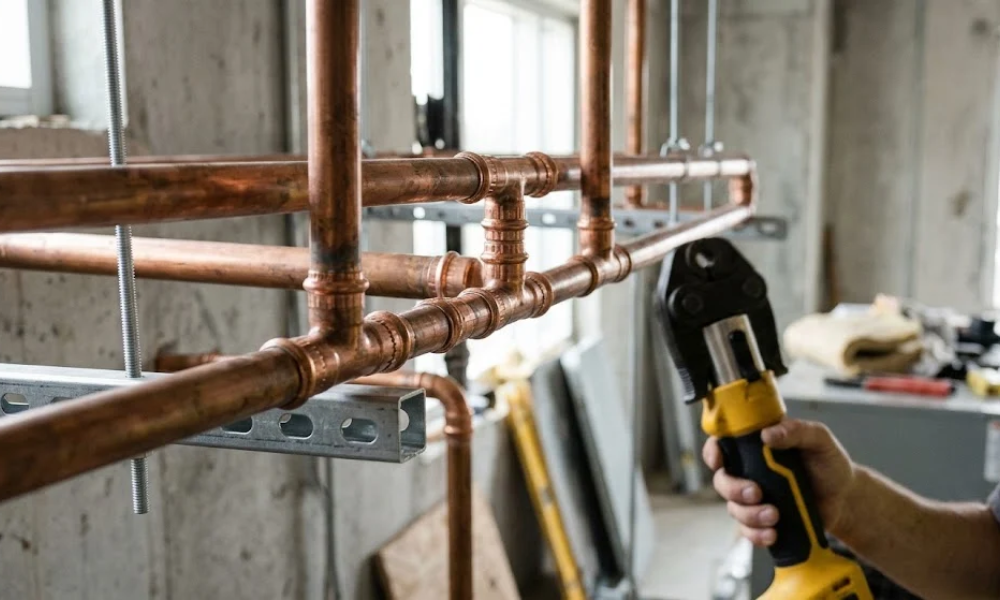
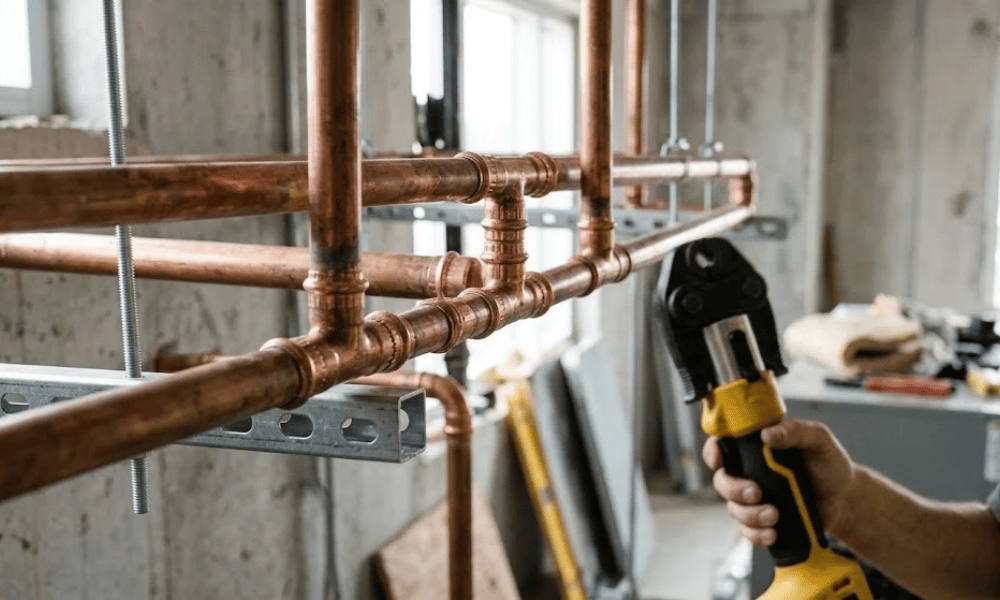
The submitting, lodged within the Western District of Tennessee on October 22, tells a narrative of a producer that went forward and resolved claims by itself. Starting in July 2025, the grievance alleges, Mueller began demanding reimbursement from James River for settlements it had already reached – involving press fittings that Mueller had manufactured, distributed, or put in at jobsites nationwide.
The issue, based on James River: no person requested first.
James River says it found throughout its investigation that Mueller had “unilaterally entered into dozens of settlements involving claims at roughly 140 areas all through 24 states.” The affected websites span California to West Virginia, with heavy clusters in Illinois, Michigan, Rhode Island, and Vermont. The submitting features a full location-by-location record. And Mueller, the grievance provides, continues to report new claims at extra websites.
What makes the protection query difficult is that not all of the fittings truly broke. In accordance with the grievance, some failed in place, some had been discovered to have failed however had not but broken surrounding property, and a few had been pulled out pre-emptively – swapped earlier than something went flawed. James River argues that the pre-emptive replacements and the no-damage failures don’t depend as coated property injury underneath Tennessee legislation, which means the coverage was by no means triggered for these claims within the first place.
Twelve methods to say no
The grievance units out 12 separate grounds for denying protection. The theme operating by all of them: James River shouldn’t be on the hook.
On the policy-language aspect, the insurer factors to a stack of normal exclusions within the major coverage. These embrace provisions barring protection for injury to the producer’s personal product, injury to its personal work, injury to property that has not truly been bodily harmed, and prices tied to the recall, inspection, or elimination of merchandise with a recognized or suspected defect. In plain phrases, James River is saying the coverage was by no means designed to cowl a producer changing its personal fittings at its personal initiative.
On the consent aspect, James River invokes two separate coverage necessities. The first coverage features a self-insured retention of $500,000 per incident – which means Mueller is answerable for the primary half-million {dollars} of every declare earlier than the insurer’s obligations start. Critically, the coverage additionally says Mueller can’t settle any declare that exceeds that threshold with out James River’s written permission. Each the first and extra insurance policies individually require that the insured not voluntarily make funds or assume obligations with out the insurer’s consent.
The grievance alleges Mueller breached each a type of necessities.
The multiplier
There’s a additional wrinkle that would dramatically enhance what Mueller owes out of pocket earlier than any protection kicks in. James River argues that underneath Tennessee legislation, every particular person website the place the fittings had been put in – or every particular person use of the fittings – counts as a separate incident. If the court docket agrees, Mueller would wish to exhaust a separate $500,000 retention for each earlier than protection applies.
Throughout 140 areas, the maths will get steep quick.
A ultimate depend alleges Mueller did not type its settlement funds into coated and uncovered classes – and that this failure to allocate, by itself, bars protection underneath each insurance policies.
What comes subsequent
The case is at its earliest stage. Mueller Industries has not but responded, and no court docket has dominated on any of the claims. How Mueller characterises its settlement exercise and see practices might be central to what comes subsequent.
The dispute is a pointy reminder that consent-to-settle provisions and voluntary-payment clauses should not boilerplate – they will every independently finish the protection dialog earlier than it begins.
The allegations within the grievance haven’t been confirmed or examined in court docket, and no decide has made any ruling on the deserves of the claims.