Q. I’m a not too long ago divorced 48-year-old girl with one son, aged 10. I earn $145,000 yearly and was given the home — my principal residence — within the divorce settlement, which is a completely paid off three-bedroom townhouse in Montreal. My ex-husband additionally pays $550 month-to-month in youngster assist that ends when my son reaches age 18. I’ve no different financial savings or investments apart from a $20,000 emergency fund. I can doubtless save $3,000 month-to-month in spite of everything bills and was questioning how I ought to save and make investments this cash. Retirement financial savings and training financial savings for my son are key priorities for me. —Stefania B. in Montreal
Reply: Hello Stefania. My suggestion to your son’s training is to contribute $5,000 a yr to a registered training financial savings plan (RESP) so that you maximize the grant. The annual contribution to get the utmost grant is $2,500. Nevertheless, you possibly can return one yr at a time to select up missed grants and the grant stops turning into out there as soon as your son turns 17. You’re doubtless going to assist your son together with his education, so why not contribute to the RESP and get the federal government grant?
It’s not as clear-cut a solution on the subject of saving for retirement. The usual technique is to maximise your registered retirement financial savings plan (RRSP) first, then your tax-free financial savings account (TFSA), adopted by non-registered investments. That’s the greatest or the worst recommendation you possibly can comply with . It’s all depending on the way you handle your cash.
I’ll present you the textbook strategy, in addition to how folks extra generally behave, then you possibly can resolve which is best for you.
To set this up I assumed inflation at two per cent and funding returns of 5 per cent, made up of a mixture of curiosity, dividends and capital positive aspects. Your dwelling bills are about $71,000 yearly, after tax and funding contributions. I additionally assumed you will have the identical $71,000-a-year after-tax revenue in retirement, which might begin in January of the yr you flip 65. Canada Pension Plan (CPP) and Outdated Age Safety (OAS) funds begin at age 65 as nicely.
I calculated the outcomes of investing $30,000 a yr, plus any tax financial savings, different year-end financial savings after spending $71,000 a yr after tax, plus the $5,000 when you cease including to the RESP. This illustrates the affect of investing the RRSP tax refund. I checked out what occurs if the cash is invested into one in every of three situations: 1. all of it goes right into a non-registered account; 2. the TFSA most plus the remaining quantity to a non-registered account and three. $30,000 to an RRSP and the excess to a TFSA after which to a non-registered account.
That is an instance of the textbook RRSP technique working. The calculations point out that below state of affairs 1, placing your cash right into a non-registered account, your financial savings at age 65 are $800,400 and financial savings are spent by age 83. With state of affairs 2, contributing to a TFSA first, you’ll have $902,000 at age 65 and you’ll spend all of it by age 87. With state of affairs 3, contributing to an RRSP first, you’ll have $1,264,200 by age 65 and it is going to be spent by age 91.
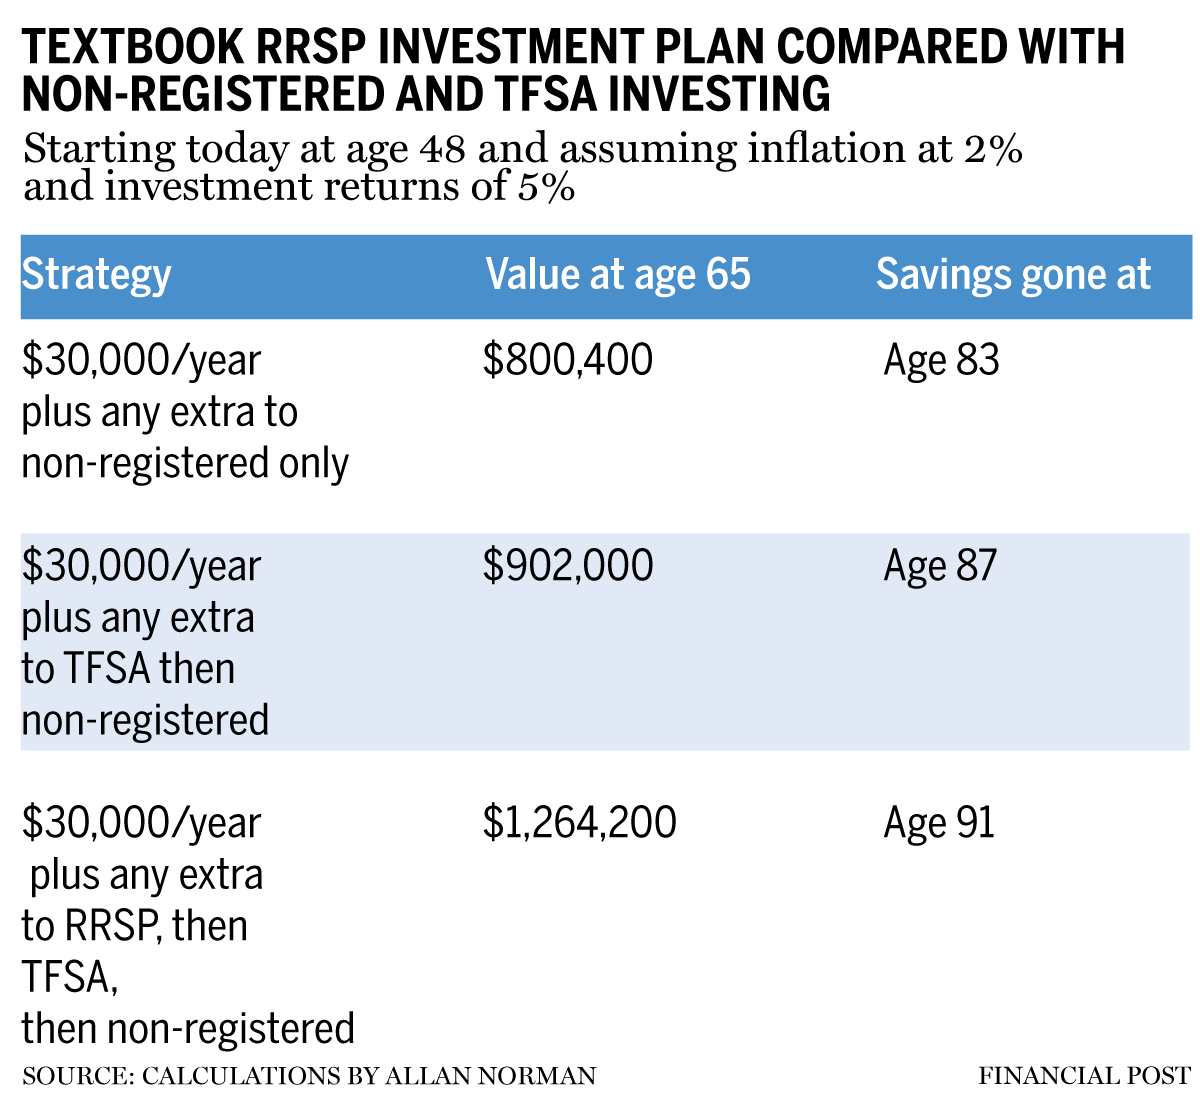
The RRSP outcomes on this state of affairs are, I really feel, consultant of what most planners and writers current.
Nevertheless, I additionally calculated situations extra reflective of how I feel most individuals really make investments, which isn’t to reinvest annual RRSP contribution tax refunds or year-end financial savings, if any. Additionally, as soon as the $5,000 RESP contributions cease, I didn’t add that to your retirement financial savings calculations.
In every State of affairs, solely $30,000 is invested annually. In state of affairs 1, all contributions go to a non-registered account. In state of affairs 2, you contribute as much as your TFSA restrict, then to a non-registered account. In state of affairs 3, you contribute as much as your RRSP restrict, then to a TFSA, then to a non-registered account. The remaining is spent.
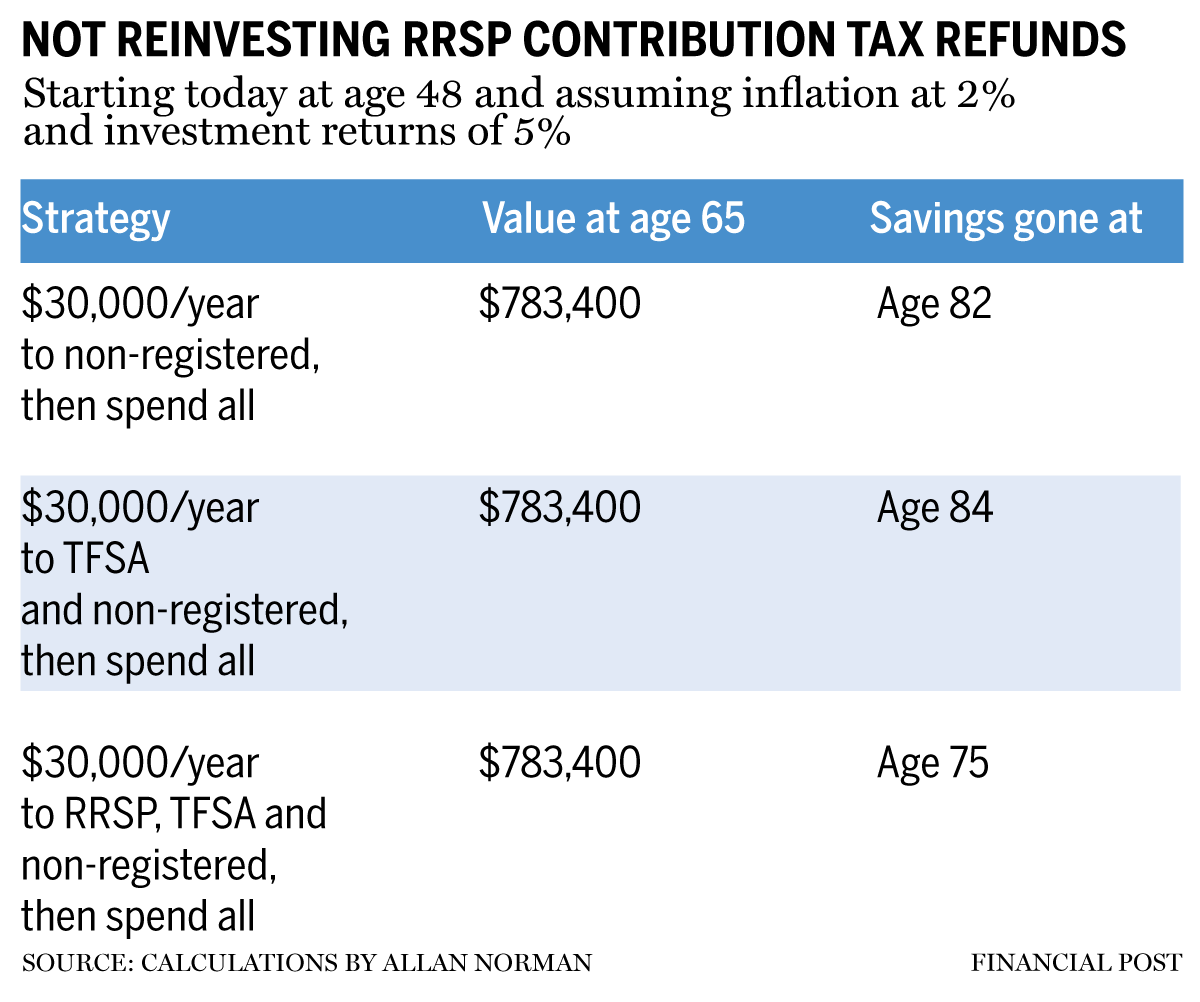
The calculations point out that below state of affairs 1, the financial savings are passed by age 82. With state of affairs 2, the cash is passed by age 84. With state of affairs 3, the cash is passed by age 75. (It is because all the cash within the registered retirement revenue fund is 100 per cent taxable when withdrawn. You must draw a bigger quantity to cowl the tax if you’d like the identical after-tax revenue.)
The massive take-away from these situations is that for those who make investments the identical fastened quantity in any of the methods you’ll have the identical worth at age 65: $783,400. Every account sort is taxed otherwise, which explains why your cash is working out at totally different ages. Cash invested in a TFSA accumulates tax free and comes out tax free. Cash invested in a non-registered account has annual distributions taxed and its progress is taxed when traded or withdrawn. Every part drawn from an RRSP or registered retirement revenue fund is 100 per cent taxable.
What’s lacking from the desk are the tax implications in the course of the accumulation section. If you end up accumulating in a non-registered account there’ll doubtless be tax owing annually and for those who don’t pay the tax out of your funding account, which most individuals don’t, it is going to come out of your free money circulate.
The RRSP seems to be to be a very unhealthy technique for those who don’t reinvest the RRSP contribution tax financial savings, though the tax financial savings are important. In case your common marginal tax charge is 40 per cent, a $30,000 RRSP contribution creates a tax financial savings of $12,000. That’s $12,000 further to reinvest or spend and do issues with, which can be extra necessary to you at this stage of your life.
Stefania, now that you understand this, do you suppose you’d reinvest the tax financial savings for those who contribute to an RRSP? If that’s the case, then the textbook RRSP technique could also be greatest for you. If not, you could be higher maximizing your TFSA first. A dialog with a monetary planner turns into helpful so you possibly can design a plan to swimsuit you and your future .
Allan Norman, M.Sc., CFP, CIM, supplies fee-only licensed monetary planning providers and insurance coverage merchandise via Atlantis Monetary Inc. and supplies funding advisory providers via Aligned Capital Companions Inc., which is regulated by the Canadian Funding Regulatory Group. He might be reached at alnorman@atlantisfinancial.ca.
Do you could have a query for FP Solutions? E mail wealth@postmedia.com.