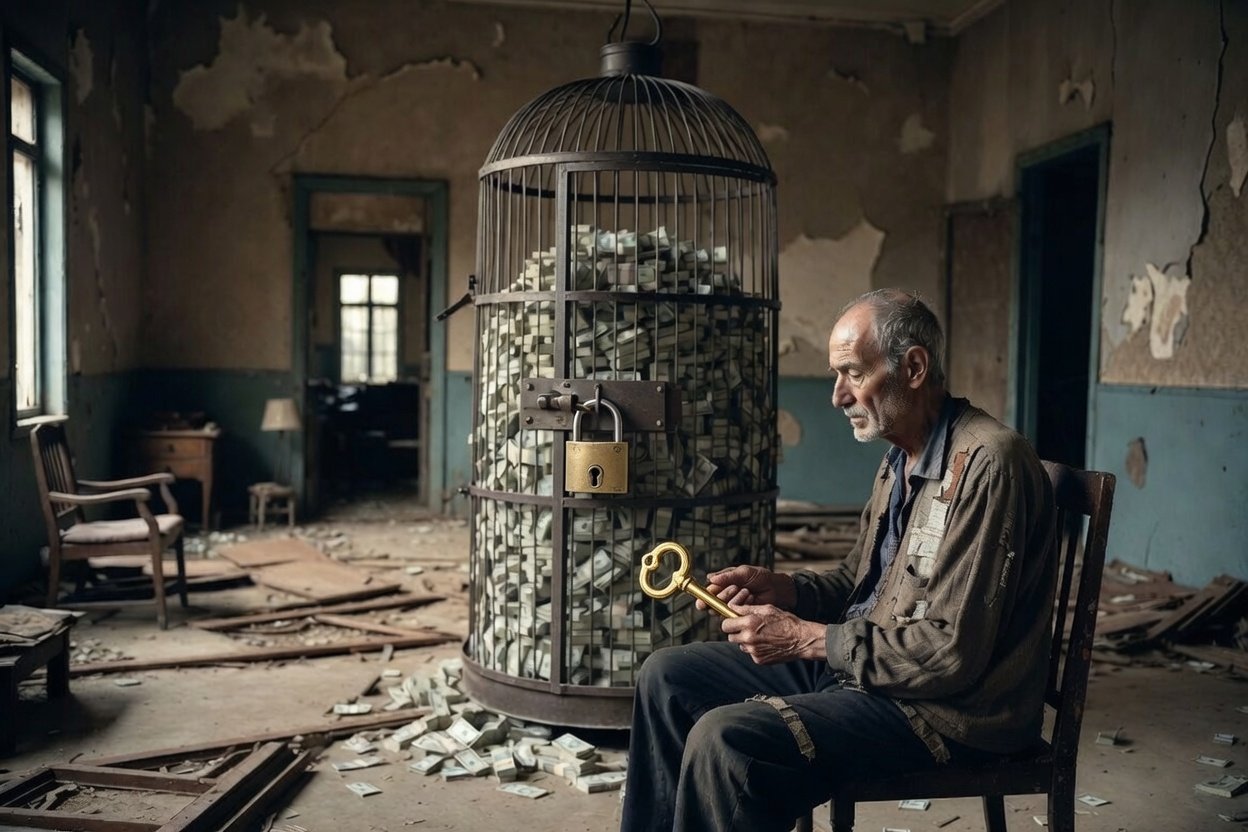
In case you wait too lengthy to start out spending your cash, you’ll have wasted a few years of pointless work, stress, and fear. You may have traded your greatest many years for a quantity on a display that ultimately will get handed to another person.
After one other summer season residing with my dad and mom, I am much more satisfied about 45, my really useful begin of decumulation. Not as a result of the mathematics modified, however as a result of I watched the choice up shut for 2 summers in a row.
Here is the belief: you will not be capable to spend all of your cash while you’re outdated. Not “you should not.” You will not be capable to. The flexibility and the will itself disappears.
And after I say outdated, I am going to peg that age at 65+, the normal retirement age when companies not deem you productive sufficient to maintain round.
The Lack of ability To Spend Cash When You are Outdated
If you wish to get a glimpse of how you will be while you’re outdated, merely spend extra time along with your dad and mom once they’re outdated. In spite of everything, youngsters are extremely influenced to observe of their father or mother’s footsteps in lots of levels of life. Spending time along with your aged dad and mom will provide you with a clue as to the way you’ll be while you’re their age.
My dad and mom used to like happening cruises to numerous components of the world. It was one of many methods they loved their wealth in retirement.
Then COVID hit and their cruising enthusiasm by no means got here again. After I requested them why they do not go anymore, they stated they cannot be bothered. Additionally they do not need to danger getting sick.
So I provided to pay. A pleasant cruise, balcony suite, any period, any location. My deal with.
They declined. This makes me unhappy as I fondly reminder seeing the enjoyment on each my father or mother’s faces each time they went to the buffet.
The only largest barrier to spending cash, the cash itself, was eliminated totally. And so they nonetheless stated no.
Upon second thought, possibly cash isn’t the most important hurdle since they’ve pensions. It’s merely simply their lack of curiosity and their want to remain wholesome.
No Excursions With The Household Both
Considered one of my favourite childhood recollections was going to Hanauma Bay with my father. We walked down and up the hill no drawback. We even bumped into Robin Williams. However after I determined to take my very own youngsters for the primary time this journey, I already knew he would not need to come, so I did not even ask.
As an alternative, he enjoys hours of free TV programming at residence. My mother does too.
So I really feel nice realizing I purchased them the biggest new TV that may match on their stand. For over a yr, that they had been watching a blurry TV, and simply chalked the picture as much as poor eyesight.
However even the best 60″ TV from a retailer now prices beneath $1,000. So low cost for years of leisure.
Cheap Board Video games
Not one to surrender simply on discovering enjoyable issues my father can do with us, I first bought him to play Monopoly Junior with my son and daughter. That labored till my boy misplaced curiosity after the primary sport. Then my daughter chucked a sport piece on the bottom after dropping a second time. Monopoly Junior is nearly totally luck, so it stops being enjoyable fairly quick.
The second night, I switched to chess, a sport my father used to play continuously. He was enthusiastic, and so have been the youngsters. Considered one of my fondest recollections is enjoying him about 10 years in the past after snow bowls for dessert. This time it was my dad versus each youngsters. They’d much more enjoyable, despite the fact that they nonetheless bought crushed.
Every sport value about $20 at Goal. They are going to be performed dozens of occasions.
That is the leisure price range of two individuals of their 70s and 80s with no debt and pensions. Board video games and a TV antenna, not even cable. The remainder of their spending is meals, taxes from required minimal distributions, home upkeep, and property taxes.
The journey and the big-ticket experiences are merely gone.
Frugality Compounds, And Not At all times In A Good Approach
Here is the half that makes it worse. My dad and mom have been frugal their total lives.
They did not grow to be cautious with cash after they retired. They have been cautious at 30, at 40, at 50, and by the point they hit their 70s, thrift wasn’t a method anymore. It was a part of their DNA.
We spend a lot time speaking about how compounding works on the asset aspect. No person warns you that it additionally works on the habits aspect. Forty years of telling your self “no” builds a muscle that will get very exhausting to chill out.
You possibly can hand a lifelong saver a spreadsheet exhibiting they will safely spend $50,000 extra a yr and they’ll nonetheless hesitate over a $12 shave ice. The quantity does not matter. The wiring does.
That is the merciless joke of the FIRE motion that no person places on a chart. The precise self-discipline that will get you to monetary independence is the factor that stops you from having fun with it.
I’ve buddies price eight figures who nonetheless will not improve their 11-year-old automotive with electrical gremlins. They don’t seem to be being good. They’re being trapped by a model of themselves from 1998 who genuinely could not afford it.
Might This Be My Future?
Whenever you’re youthful, it is simple to say your life will look totally different out of your dad and mom’ while you get to their age. Then you definitely catch your self doing the very same issues.
I keep in mind when my dad was 49, as a result of I used to be 17, ending up my senior yr of highschool and entering into a good quantity of bother. He labored a daily job and got here residence with my mother round 5:30 or 6pm.
So we’re totally different in that respect. I ended working a day job 5 years earlier than we had our son.
However I forgot that my dad and I used to play golf collectively every time I got here residence to Honolulu. That hasn’t occurred in about 10 years. He misplaced curiosity and bodily mobility. There was not sufficient time or motivation to get on the market.
Here is the factor. I do not discover golf that enjoyable anymore both after being infatuated with the game in my 30s. I solely go when somebody invitations me to a company outing or their membership, which is barely two or thrice a yr. I might moderately play pickleball and tennis, however my physique is carrying down too with rising accidents.
Since graduating from faculty in 1999, I’ve by no means gotten into the behavior of watching greater than two hours of TV a day. Most days I watch none, simply quick video clips on-line. In spite of everything, I lower cable, keep in mind this yr. A very long time in the past I made a decision producing content material was extra enjoyable than consuming it. It was additionally extra worthwhile.
But when I do not find yourself watching quite a lot of TV as my low cost leisure, I am going to most likely simply play pickleball, go to the seashore, or go climbing as a substitute. Shock shock, all of these are free.
So after I was going through a liquidity crunch and my spouse wished us to trip in Las Vegas, I made a decision to YOLO. I wasn’t going to let my silent stress maintain us from a memorable expertise.
How About Spending On Vehicles And Homes?
My dad and mom drive a 28-year-old automotive. Meaning my dad has been driving the identical car since he was 54 and I used to be 21. At 49, I am not that far behind. I’ve had my 2015 automotive, purchased a yr outdated, for 10 years now.
I might simply see myself maintaining my subsequent automotive till it disintegrates. The thrill of proudly owning a flowery new automotive died for me round age 32. Now I would like dependable, secure, and roomy sufficient for a household of 4. As soon as each youngsters are out of the home, I am unsure I am going to want to purchase something nicer. I solely drive 6,300 miles a yr as it’s.
Lastly, my dad and mom dwell in a paid-off residence my grandparents constructed within the Eighties, after tearing down the earlier home that was infested with termites. The home is just too large for them, however it’s nice after we go to, particularly now that I’ve completed transforming the two-bedroom in-law unit.
Except they need to transfer right into a two or three-bedroom condominium with facilities, they are not spending cash on property both.
We discovered our eternally residence in San Francisco after climbing the property ladder for 20 years. We cannot be upgrading if we keep within the metropolis. If we transfer to Honolulu, we’d purchase a less expensive home since costs are extra inexpensive there.
Hmm. Virtually each single line is me turning into my father, simply on a 33-year delay.
Spending Cash Aggressively Previous 65 Gives Declining Pleasure
Ages 65 to 70 just isn’t that outdated, assuming your well being is unbroken. However I’ve clearly watched my dad and mom decelerate after 70.
Apart from yummy meals and health, there’s genuinely nothing cash can purchase them that brings extra pleasure. The one factor I got here up with is hiring a dependable home cleaner as soon as a month for $500. And even that may come out of their money stream, not financial savings or investments.
Which suggests the one manner my dad and mom will ever decumulate their wealth is by means of a bear market. A decline that gives them nothing in return. That is it. That is the exit.
Their cash is not going to be spent. It can merely be transferred, both to the market on a foul yr or to me and my sister.
However, I do not need it. I’ve my very own cash. I constructed my very own factor particularly so I’d by no means have to consider theirs. Each greenback they do not spend just isn’t a greenback I am quietly rooting for. It is a therapeutic massage they did not get, a cruise they did not take, a enterprise class seat they suffered by means of coach to keep away from.
I might commerce your entire the rest for 2 extra good years of them having fun with themselves.
15-20-Yr Window To Spend With Pleasure When Outdated
So after I take a look at my life at 49, and at their lives after retiring of their 60s, it turns into apparent that there is solely a few 15-20-year window to spend cash deliberately.
You do not need to spend closely earlier than 45, as a result of there’s an excessive amount of life left and doubtless dependents to take care of. However after 45, it is go time. That window closes sooner than anybody expects, and it closes from the within.
In case you FIREd nicely earlier than 65, paradoxically, chances are you’ll have to spend much more aggressively. You amassed sufficient capital to retire early within the first place, which implies you benefited extra from the bull market than the common employee who cannot dwell off investments alone.
A 4% and even 5% secure withdrawal fee has merely been too conservative since 2012. Your web price is way increased than while you first retired.
What I am Truly Going To Do About It
After observing my dad and mom intimately for 2 straight summers, I’ll work tougher at consumption spending.
I attempted my greatest with the $40,000 earmarked for the Summer time YOLO Fund and failed spectacularly, spending solely 20% of it. However I nonetheless spent greater than I’d have with out setting an intentional goal, so the train wasn’t a complete waste. I additionally used the remaining funds to put money into Mezzi, the AI funding advisor I feel is extremely useful.
America typically thinks spending cash on non-public college is a waste. I do not, in order that expense is roofed. My residence is about for now, although I am contemplating one thing nicer in Honolulu.
What’s left is upgrading my automotive, consuming absurdly costly meals I do not want, and donating extra to charity.
I’ve additionally bought to cease treating investing like a luxurious expense. Investing has been certainly one of my largest hobbies for the previous 30 years, and it is nearly not possible to cease. It brings me a lot pleasure!
Lastly, I might like to dwell lengthy sufficient to see and assist handle my grandchildren. Therefore, extra money to bodily and psychological well being.
The Humorous Half Of Not Spending
Paradoxically, my dad and mom appear completely satisfied. Or possibly the higher phrase is content material.
In case you requested them whether or not they’re lacking out on something, they’d take a look at you such as you requested whether or not they’re lacking out on scuba diving. By no means.
So who precisely is the sad one right here?
Perhaps I am projecting. Perhaps I am their life by means of the eyes of a 49-year-old with a functioning physique and a to-do checklist, and mistaking a calmer life for a lesser one.
Or possibly contentment is simply what a lifetime of frugality seems like from the within, and there is no strategy to inform the distinction between peace and adaptation from the surface.
I do not know.
For myself, the lesson is easier. Entrance-load the spending after age 45. Do the journey whereas your knees work. Purchase the factor whilst you nonetheless need issues.
As a result of the cash will completely nonetheless be there at 75. You are the half that will not be.
Reader Questions
Have you ever watched a father or mother grow to be unable to spend their cash, even once they clearly might afford to? At what age did the shift occur?
In case you’re a lifelong saver, what is the largest purely discretionary buy you have made previously yr, and the way lengthy did you agonize over it?
Do you imagine you will spend extra freely in retirement than your dad and mom did, or is that the identical factor each technology tells itself at 49?
If you wish to know the way a lot you possibly can truly spend down with out operating out, you should see the whole lot in a single place first. I have been utilizing Empower’s free monetary instruments since 2012 to trace my web price, x-ray my portfolio for hidden charges, and run their Retirement Planner. The planner is what satisfied me my secure withdrawal fee was too conservative within the first place.
Most individuals spend too little in retirement as a result of they’ve by no means modeled what “an excessive amount of” would truly appear like. Run the numbers and discover out the place your actual ceiling is. It is free to enroll and takes about 10 minutes to hyperlink accounts.
In case you hyperlink over $100,000 in investable belongings, you possibly can schedule a free monetary evaluation with an expert. I’ve achieved so thrice previously 14 years, and every time has been useful in highlighting potential blindspots to assist me construct extra wealth.
Publication Signup
If a buddy forwarded you this submit, welcome. Be a part of 60,000+ readers who get my free weekly publication at financialsamurai.com/information.
You may as well get notified the second new posts publish by signing up at financialsamurai.com/e-mail. Posts exit ad-free for the primary few hours to subscribers.
Every little thing I write comes from firsthand expertise, as a result of cash is just too necessary to be left as much as pontification. I have been sharing it since 2009.