The first frontrunner desires a flooring on claims payouts and a state-run catastrophe pool. Her opponent and a number of other business voices say the numbers do not work
Image: Jane Kim, This file is licensed beneath the Inventive Commons Attribution 2.0 Generic license
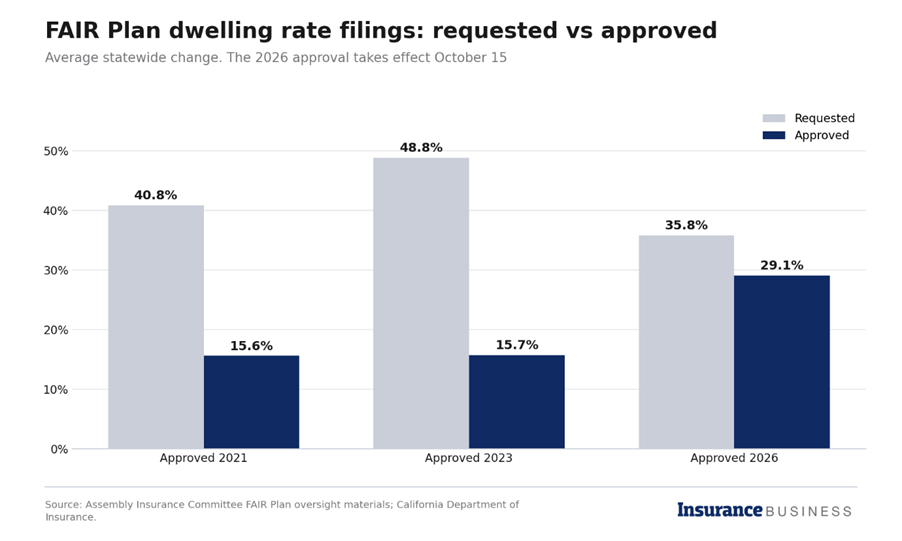
California’s insurer of final resort will begin billing new and renewing prospects a mean of 29.1% extra on October 15. Voters select the state’s subsequent insurance coverage commissioner 19 days later, and the candidate who gained the June main is campaigning on the concept the market wants greater than a charge repair.
Jane Kim, a former San Francisco supervisor and director of the California Working Households Get together, advised reporters this week that the system because it stands “is a catastrophe.” Her platform would change how carriers are measured on claims, how the FAIR Plan is ruled, and who carries wildfire danger within the state.
She faces state Sen. Ben Allen, a fellow Democrat. CalMatters reviews it’s the first time for the reason that workplace turned elective that two Democrats have met within the common election. Commissioner Ricardo Lara is term-limited after eight years.
A backstop that stored rising
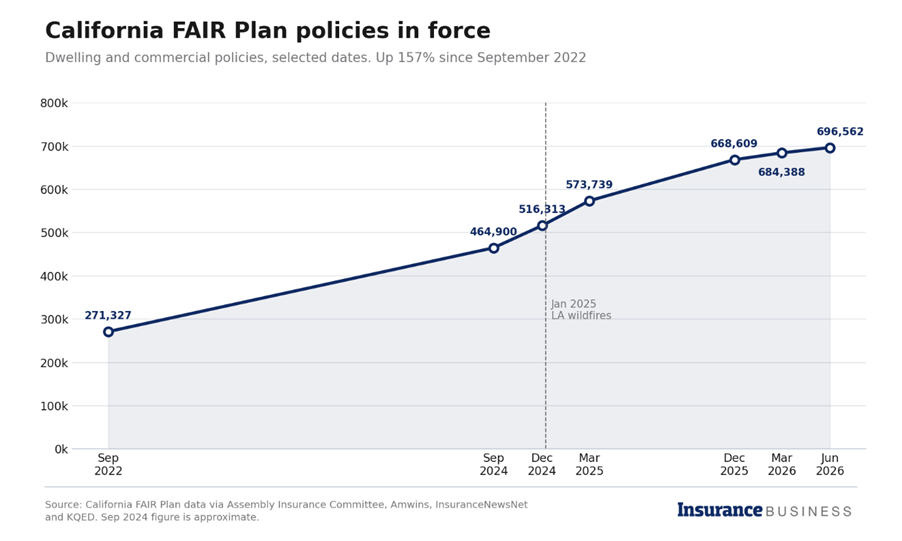
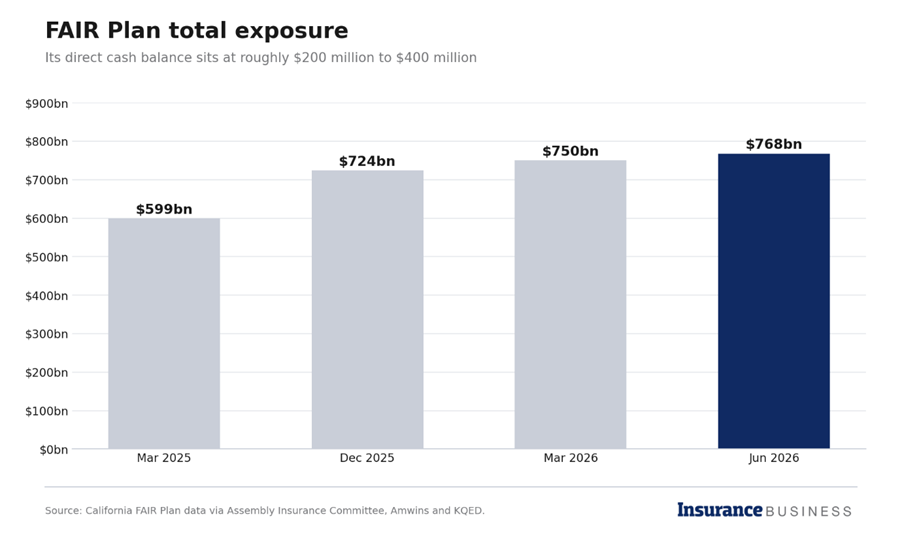
The FAIR Plan had 696,562 dwelling and business insurance policies in pressure in June, up 157% from September 2022, in accordance with plan figures. Its publicity has climbed to $768 billion. Its direct money steadiness is between $200 million and $400 million, so it depends on reinsurance, bonds and assessments on member insurers to pay a big disaster.
Karl Susman, a Los Angeles dealer, advised KQED the October improve is “undoubtedly going to trigger ache for some individuals.” Prospects in excessive wildfire-risk areas will take the most important hits, and a few will see the wildfire portion of their premium double.
The October improve can also be the primary time in latest filings that regulators accepted most of what the plan requested for. In 2021 and 2023, the Division of Insurance coverage lower FAIR Plan requests of 40.8% and 48.8% to about 16% every, in accordance with Meeting Insurance coverage Committee oversight supplies. This time the plan sought 35.8% and obtained 29.1%.
Premiums within the voluntary market have been rising too. A Stanford evaluation launched in June discovered common owners premiums up 84% for the reason that finish of 2020, or 45% after inflation. Insurance coverage Enterprise coated the figures in its have a look at how the commissioner race impacts brokers within the nation’s hardest market.
The Division of Insurance coverage says the FAIR Plan’s development is slowing. The plan added about 16,000 residential insurance policies within the first quarter of 2026. Between 2024 and September 2025, it had been including 35,000 to 50,000 1 / 4.
Kim says that’s not sufficient. “The present establishment is just not an possibility,” she advised KPBS.
What Kim says she would change
A flooring on claims payouts. Kim desires dwelling and auto insurers held to a minimal loss ratio, just like the one the Inexpensive Care Act units for well being plans. She says Californians get again about 48 cents in claims for every premium greenback and needs a flooring of roughly 65 to 75 cents. The business is prone to dispute her baseline. A Triple-I report citing AM Greatest information discovered California owners insurers ran a mean mixed ratio of 122.6 from 2016 by means of 2025, which means they paid out extra in claims and bills than they collected. Insurance coverage Enterprise reported these figures when it discovered that 15% of California’s owners market is now nonstandard.
Curiosity on delayed claims. Insurers would owe policyholders curiosity for every day a legitimate declare is denied, delayed or underpaid.
FAIR Plan governance. Kim notes that the plan was created in 1968 to counter redlining, and says its insurer-run governing committee operates with little public visibility. She would audit the committee and add seats for shopper advocates, the governor’s workplace and the Division of Insurance coverage. She factors to Florida’s insurer of final resort, Residents Property Insurance coverage Corp., which is a public nonprofit, as a mannequin.
Pure Catastrophe Insurance coverage for All. Her signature proposal is a state-run pool funded by redirecting a part of the premiums Californians already pay. Among the pool’s funding returns would go towards fireproofing, floodproofing and different mitigation. She cites New Zealand, France and Spain as precedents and says this system can be phased in.
Learn subsequent: Jane Kim leads California insurance coverage commissioner race – report
The case in opposition to what she’s proposing
Allen has known as the catastrophe pool a “pie within the sky” thought, in an interview with ABC7. The San Francisco Chronicle’s editorial board endorsed Allen and described Kim as rash, warning that her strategy may undo latest progress and destabilize the market.
Patrick Wolff, who ran within the main and now backs Allen, argued within the San Francisco Commonplace that not one of the nationwide applications Kim cites covers hearth. He wrote that New Zealand’s Pure Hazards Fee affords capped first-layer cowl for occasions reminiscent of earthquakes and landslides, with personal insurers protecting hearth. He additionally argued that California’s Prop 103 laws already restrict insurers’ allowable earnings.
Even Jamie Court docket, president of Shopper Watchdog, has publicly questioned whether or not a state fund may increase the tens of billions of {dollars} it might have to survive one dangerous hearth season.
Kim advised KPBS she accepts the criticism that she desires an excessive amount of for California. She argues that sticking with the present strategy is the larger danger.
Learn subsequent: FAIR Plan charge hike provides to California owners insurance coverage pressure
Allen’s pitch
Allen represents Pacific Palisades within the state Senate. He has stated the January 2025 fires are why he entered the race. He desires to make the admitted market work higher somewhat than exchange it.
“There is not any silver bullet right here,” he advised the San Francisco Examiner. He listed rate-review reform, statewide danger discount, higher information, stronger shopper protections and FAIR Plan stabilization as his priorities.
On his marketing campaign web site, Allen argues that FAIR Plan development drives up prices for all policyholders, not simply these on the plan, and says the objective must be shifting as many householders as attainable again to the standard market. He authored Proposition 4, the local weather bond voters accepted in 2024.
The place they stand
|
Jane Kim
|
Ben Allen
|
|
|
Market construction
|
State-run catastrophe pool alongside personal market
|
Stabilize and develop the admitted market
|
|
FAIR Plan
|
Audit governance, add public seats
|
Enhance solvency and claims dealing with, transfer policyholders out
|
|
Claims
|
Minimal loss ratios, curiosity on delayed claims
|
Stronger enforcement of present claims legal guidelines
|
|
Key backers
|
Sen. Bernie Sanders, labor unions
|
California Democratic Get together, Sens. Adam Schiff and Alex Padilla
|
The political image
Kim completed first in June with 27.2% to Allen’s 19.3%, with 95% of ballots counted. Republican Stacy Korsgaden, an insurance coverage agent, was third. Allen later gained the formal endorsement of the California Democratic Get together.
What brokers and carriers inherit
The winner takes over Lara’s Sustainable Insurance coverage Technique. Beneath it, carriers can use disaster fashions and reinsurance prices in charge filings in the event that they decide to writing not less than 85% of their statewide market share in wildfire-distressed areas. Six of the state’s 10 largest dwelling insurance coverage teams had signed on by mid-2026.
The technique’s outcomes are contested. Shopper Watchdog counts about 12,189 new-policy commitments for the reason that guidelines took impact, set in opposition to $571 million in requested or accepted charge will increase, in accordance with CalMatters. The division known as that rely incomplete and untimely.
David Russell, a professor of insurance coverage and finance at Cal State Northridge, advised CalMatters that “insurers are tiptoeing again into the market.”
A Kim administration would doubtless take a tougher line on charge will increase filed beneath the technique, and on claims dealing with and FAIR Plan oversight. Allen can be extra prone to maintain the framework and alter it. Whoever wins, FAIR Plan and surplus traces insurance policies already account for about 15% of California’s owners market.
Learn subsequent: California declares state of emergency
KPBS says it’s working to schedule an interview with Allen. The election is November 3.