

Key Factors
- The Division of Schooling’s official FY 2023 cohort default fee is 0.4%, up from 0.0% for FY 2022. Simply 14,296 of the three.37 million debtors within the cohort defaulted through the three-year measurement window.
- The speed is low as a result of the pandemic fee pause, the on-ramp, and the SAVE forbearance lined almost all the window.
- The quantity that issues is coming subsequent 12 months. Draft FY 2024 charges arrive in early 2027 and would be the first calculated with no pandemic protections in place, and roughly 1,800 faculties have already got nonpayment charges of 25% or greater.
The Division of Schooling launched its official FY 2023 pupil mortgage cohort default fee on September 30, 2026, and the headline determine is 0.4%. Amongst 3,372,244 debtors who entered reimbursement between October 1, 2022, and September 30, 2023, solely 14,296 defaulted by September 30, 2025, in line with the Federal Pupil Help briefing. That’s the fourth straight 12 months the nationwide fee has landed at or close to zero, but it surely bears no resemblance to the 9.3 million debtors at the moment in default on federal loans.
The hole between these two numbers is complicated lots of people, together with monetary support places of work. The reason will not be that debtors out of the blue began paying. It’s that the cohort default fee is a slim, backward-looking measure, and the pandemic-era protections occurred to cowl almost day by day of the window it measures.
Mainly, in case you see this quantity, disregard it. It’s not useful… but. Right here’s what to know.
Would you want to avoid wasting this?
How The Cohort Default Charge Really Works
A cohort default fee tracks one group of debtors, those that entered reimbursement throughout a single federal fiscal 12 months, and asks what share of them defaulted by the top of the second fiscal 12 months after that. For the FY 2023 cohort, the window opened October 1, 2022, and closed September 30, 2025. Default, for this function, means a mortgage has gone a minimum of 270 days and not using a fee.
The speed is calculated for each faculty that participates in federal support, and the nationwide determine is just the sum of these faculties. The FY 2023 calculation lined 5,417 establishments.
Congress constructed the measure as an accountability software: beneath the Greater Schooling Act, a college with a CDR of 30% or greater for 3 consecutive years, or above 40% in a single 12 months, loses entry to federal pupil loans, and for-profit faculties have traditionally been the colleges closest to these strains.
The lag is by design. As a result of the window runs three fiscal years and the Division wants most of one other 12 months to finalize the information, an official CDR describes debtors who left faculty roughly 4 years earlier than the quantity is printed. The FY 2023 fee launched this week was calculated on August 1, 2026, about debtors who began reimbursement in late 2022 and early 2023.
.tci-chart{
–bg:#ffffff; –ink:#1a1a1a; –ink-2:#555; –ink-3:#8a8a8a;
–grid:#e6e6e6; –line:#1f5fa8; –band:rgba(31,95,168,.08); –band-ink:#1f5fa8;
–tip-bg:#1a1a1a; –tip-ink:#fff;
}
@media (prefers-color-scheme: darkish){ .tci-chart{
–bg:#121417; –ink:#f2f2f2; –ink-2:#b8b8b8; –ink-3:#8a8a8a;
–grid:#2a2d31; –line:#6aa7e8; –band:rgba(106,167,232,.12); –band-ink:#6aa7e8;
–tip-bg:#f2f2f2; –tip-ink:#121417;
} }
.tci-chart{max-width:760px;margin:0 auto;padding:16px;}
.tci-chart h3{font-size:18px;line-height:1.3;margin:0 0 4px;font-weight:600;}
.tci-chart p.sub{font-size:14px;coloration:var(–ink-2);margin:0 0 12px;}
.tci-chart .wrap{place:relative;}
.tci-chart svg{width:100%;peak:auto;show:block;overflow:seen;}
.tci-chart .grid line{stroke:var(–grid);stroke-width:1;}
.tci-chart .axis textual content{fill:var(–ink-3);font-size:12px;font-variant-numeric:tabular-nums;}
.tci-chart .collection{fill:none;stroke:var(–line);stroke-width:2;stroke-linejoin:spherical;stroke-linecap:spherical;}
.tci-chart .dot{fill:var(–line);stroke:var(–bg);stroke-width:2;}
.tci-chart .hit{fill:clear;cursor:pointer;}
.tci-chart .lbl{fill:var(–ink);font-size:12px;font-weight:600;}
.tci-chart .band{fill:var(–band);}
.tci-chart .band-lbl{fill:var(–band-ink);font-size:11px;font-weight:600;letter-spacing:.02em;}
.tci-chart .crosshair{stroke:var(–ink-3);stroke-width:1;opacity:0;}
.tci-chart .tip{place:absolute;pointer-events:none;background:var(–tip-bg);coloration:var(–tip-ink);font-size:12px;line-height:1.35;padding:6px 8px;border-radius:4px;white-space:nowrap;opacity:0;rework:translate(-50%,-100%);transition:opacity .08s;}
.tci-chart .tip b{font-weight:600;}
.tci-chart .foot{font-size:12px;coloration:var(–ink-3);margin-top:8px;line-height:1.4;}
.tci-chart particulars{margin-top:8px;font-size:13px;}
.tci-chart abstract{cursor:pointer;coloration:var(–ink-2);}
.tci-chart desk{border-collapse:collapse;margin-top:8px;font-variant-numeric:tabular-nums;}
.tci-chart td, .tci-chart th{padding:3px 12px 3px 0;text-align:left;border-bottom:1px stable var(–grid);}
.tci-chart th{coloration:var(–ink-2);font-weight:600;}
Official Nationwide Pupil Mortgage Cohort Default Charge, FY 2012–FY 2023
Share of debtors coming into reimbursement every fiscal 12 months who defaulted throughout the three-year measurement window
View as desk
| Cohort | Official CDR |
|---|
(operate(){
const information=[
[“FY 2012”,11.8],[“FY 2013”,11.3],[“FY 2014”,11.5],[“FY 2015”,10.8],
[“FY 2016”,10.1],[“FY 2017”,9.7],[“FY 2018”,7.3],[“FY 2019”,2.3],
[“FY 2020”,0.0],[“FY 2021”,0.0],[“FY 2022”,0.0],[“FY 2023″,0.4]
];
const svg=doc.getElementById(‘cdr’), NS=’http://www.w3.org/2000/svg’;
const W=728,H=360,m={t:34,r:24,b:40,l:40};
const iw=W-m.l-m.r, ih=H-m.t-m.b;
const x=i=>m.l+ i*(iw/(information.length-1));
const y=v=>m.t+ih-(v/12)*ih;
const el=(n,a,p)=>svg).appendChild(e);return e;;
// pandemic band: FY2019 to FY2023 cohorts
const step=iw/(information.length-1);
const bx=x(7)-8, bw=x(11)-x(7)+16;
el(‘rect’,{class:’band’,x:bx,y:m.t-8,width:bw,peak:ih+8,rx:4});
const bl=el(‘textual content’,{class:’band-lbl’,x:bx+bw-4,y:m.t-14,’text-anchor’:’finish’});
bl.textContent=”FY 2019 TO FY 2023 COHORTS: PAUSE IN WINDOW”;
// grid + y axis
const g=el(‘g’,{class:’grid’}), ax=el(‘g’,{class:’axis’});
[0,3,6,9,12].forEach(v=>{
el(‘line’,{x1:m.l,x2:W-m.r,y1:y(v),y2:y(v)},g);
const t=el(‘textual content’,{x:m.l-8,y:y(v)+4,’text-anchor’:’finish’},ax); t.textContent=v+’%’;
});
information.forEach((d,i)=>{
const t=el(‘textual content’,{x:x(i),y:H-m.b+20,’text-anchor’:’center’},ax); t.textContent=d[0].substitute(‘FY ‘,”);
});
const fy=el(‘textual content’,{x:m.l,y:H-m.b+36,’text-anchor’:’begin’},ax); fy.textContent=”Fiscal 12 months cohort”;
// line
const path=information.map((d,i)=>(i?’L’:’M’)+x(i)+’,’+y(d[1])).be part of(‘ ‘);
el(‘path’,{class:’collection’,d:path});
// dots + selective labels
information.forEach((d,i)=>{ el(‘circle’,{class:’dot’,cx:x(i),cy:y(d[1]),r:4}); });
const label=(i,txt,dx,dy,anchor)=>{const t=el(‘textual content’,’center’);t.textContent=txt;};
label(0,’11.8%’,0,-10);
label(6,’7.3%’,0,-10);
label(7,’2.3%’,-10,4,’finish’);
label(11,’0.4%’,0,-10);
// crosshair + tooltip
const ch=el(‘line’,{class:’crosshair’,y1:m.t,y2:m.t+ih});
const tip=doc.getElementById(‘tip’), wrap=svg.parentElement;
information.forEach((d,i)=>{
const h=el(‘rect’,{class:’hit’,x:x(i)-step/2,y:m.t,width:step,peak:ih});
const present=()=>{
ch.setAttribute(‘x1’,x(i));ch.setAttribute(‘x2′,x(i));ch.fashion.opacity=1;
tip.innerHTML=’‘+d[0]+’ cohort
Official CDR: ‘+d[1].toFixed(1)+’%’;
const r=wrap.getBoundingClientRect(), s=r.width/W;
tip.fashion.left=(x(i)*s)+’px’; tip.fashion.high=(y(d[1])*s-12)+’px’; tip.fashion.opacity=1;
};
const disguise=()=>{ch.fashion.opacity=0;tip.fashion.opacity=0;};
h.addEventListener(‘mouseenter’,present);h.addEventListener(‘mousemove’,present);
h.addEventListener(‘mouseleave’,disguise);h.addEventListener(‘touchstart’,present,{passive:true});
});
// desk
const tb=doc.querySelector(‘#tbl tbody’);
information.forEach(d=>{const tr=doc.createElement(‘tr’);tr.innerHTML=’
})();
Why 4 Years Of Close to-Zero Charges Imply Nothing
The Division’s personal briefing says the FY 2023 fee “ought to be interpreted with warning.” The reason being a stack of three overlapping protections. The pandemic fee pause started March 13, 2020, and ran via September 2023, with no Federal pupil loans coming into default throughout that stretch.
When funds resumed in October 2023, the Division added a 12-month on-ramp via September 30, 2024, throughout which missed funds weren’t reported to credit score bureaus and debtors couldn’t be positioned in default. Then the courts blocked the SAVE plan, and the roughly 7 million debtors enrolled in it had been positioned in a litigation forbearance that stretched from July 2024 into the autumn of 2025.
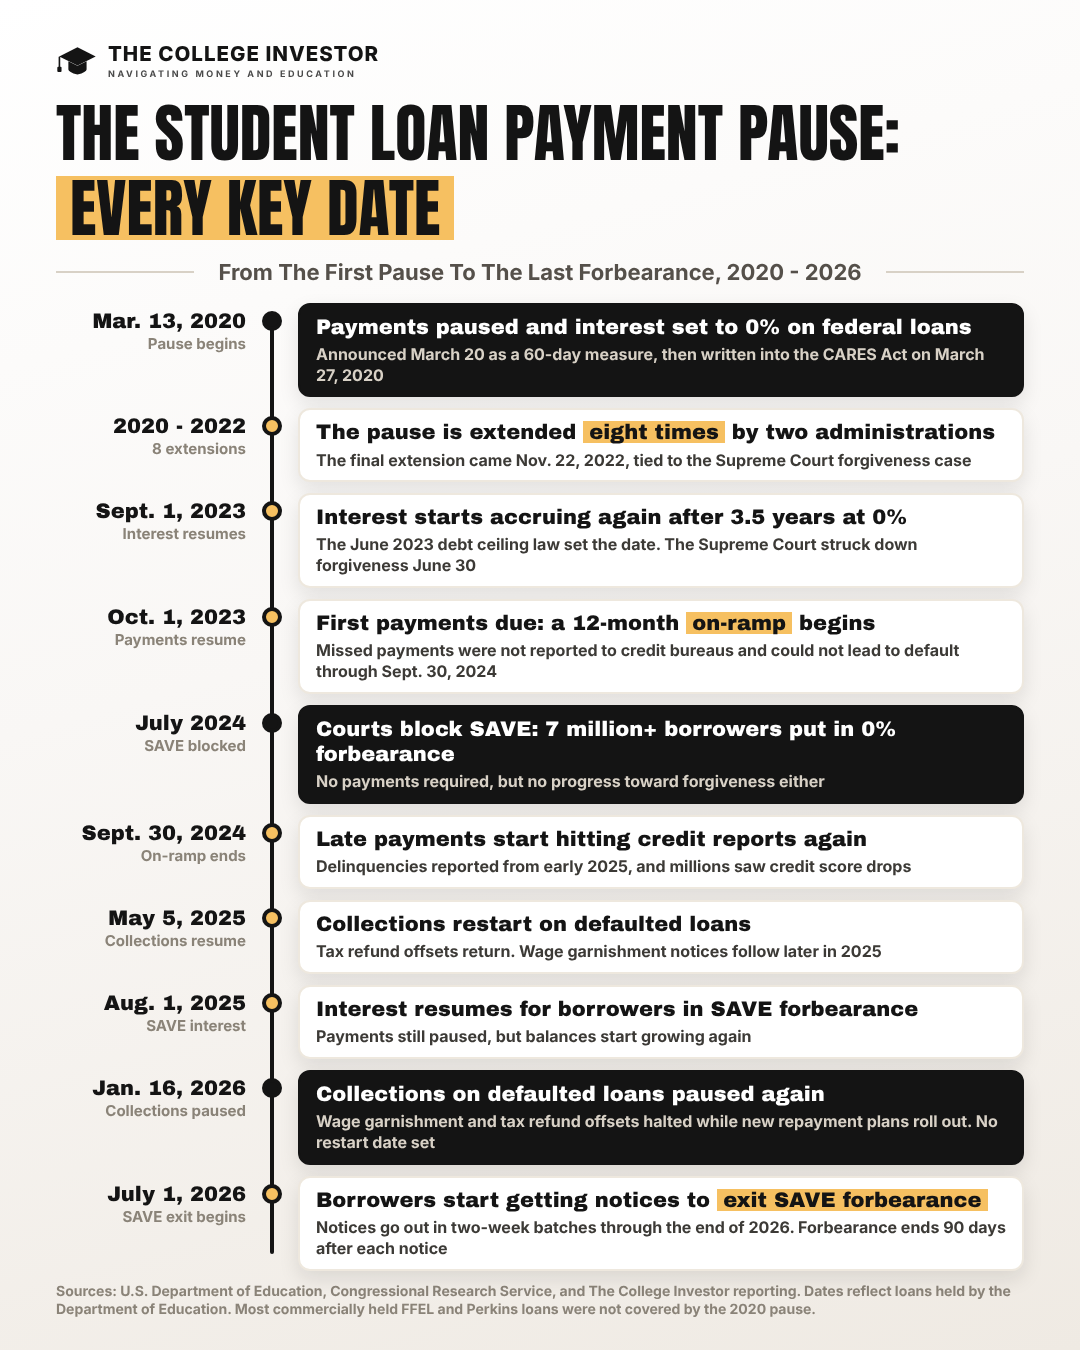
Lay these dates over the FY 2023 window and the maths turns into apparent. The Nationwide Affiliation of Pupil Monetary Help Directors calculates that FY 2023 debtors had precisely 12 months, October 2024 via September 2025, during which it was even potential to turn into delinquent lengthy sufficient to hit the 270-day threshold, and SAVE debtors had been shielded for many of that 12 months. The FY 2022 cohort had zero such days, which is why its fee was 0.0%. For comparability, the final absolutely pre-pandemic cohort, FY 2018, defaulted at 7.3%, and FY 2016 got here in at 10.1%.
The distortion truly begins one 12 months sooner than most individuals assume. The FY 2019 cohort entered reimbursement between October 2018 and September 2019, and its monitoring window ran via September 30, 2021. The pause arrived on March 13, 2020, roughly midway via, and it did two issues without delay: funds stopped being required, and the delinquency clock froze for anybody already behind. A borrower who was 200 days late in March 2020 stayed at 200 days for the subsequent three and a half years as a substitute of crossing the 270-day line.
That left FY 2019 debtors with someplace between 5 and 17 months of actual publicity, relying on after they entered reimbursement, as a substitute of the standard three years. The consequence was a 2.3% fee, down from 7.3% the 12 months earlier than. The nationwide fee had been declining slowly since FY 2012, when it peaked at 11.8%, however a five-point drop in a single cohort will not be a development. It’s a window that closed early, and each cohort since has had the identical downside or worse.
What The Numbers Present Beneath The 0.4%
Even inside a near-zero 12 months, the information is exhibiting a number of alerts. Debtors at for-profit faculties defaulted at 0.8%, double the 0.3% fee at private and non-private nonprofit establishments, with 4,821 of 576,634 proprietary-school debtors in default. Overseas faculties posted the bottom fee at 0.2%.
The cohort itself additionally shrank. The variety of debtors coming into reimbursement fell 4.4% from the FY 2022 cohort, a drop of 156,845 individuals, and the decline at for-profit faculties was 13.4%. The variety of taking part faculties fell by 88, to five,417, with for-profits accounting for 83 of the misplaced establishments.
These shifts monitor with enrollment and lending developments The School Investor has lined, the place fewer college students are borrowing whilst balances for many who do preserve rising.
The Quantity Faculties Ought to Be Watching As a substitute
The Division is telling faculties to deal with a unique metric: the nonpayment fee. That determine measures the share of a college’s Direct Mortgage debtors who entered reimbursement between January 2020 and Could 2025 and are greater than 90 days delinquent. The Division refreshed that information on September 22, 2026, utilizing August 2026 figures, and the outcomes present a a lot larger concern.
Roughly 1,800 establishments have nonpayment charges at or above 25%, in line with the Division’s announcement. That’s in line with the broader delinquency image: as of June 30, 2026, Federal Pupil Help information confirmed 9.3 million debtors in default holding $234 billion, with one other 1.5 million in late-stage delinquency and roughly 20% of debtors in lively reimbursement greater than 30 days behind.
The nonpayment fee carries no sanctions. The CDR does, and the Division’s announcement spells out what it expects: draft FY 2024 charges will probably be issued in early 2027, and the official FY 2024 charges subsequent fall will probably be “the primary such launch following the complete expiration of pandemic-era flexibilities.”
The Division has requested faculties above 25% to replace their default prevention plans, attend an October 13 webinar, and full a brand new self-paced coaching monitor on CDRs. The FY 2024 cohort entered reimbursement between October 2023 and September 2024, and its window closes September 30, 2026, that means the result is already largely baked in.
What This Means For Debtors And Households
For a person borrower, the CDR has no direct impact in your mortgage. It doesn’t change your rate of interest, your reimbursement plan choices, or whether or not your mortgage is in good standing. Its impact is on the varsity, and solely when it crosses the sanction thresholds.
The oblique results are those price listening to. A faculty that loses federal mortgage eligibility loses the income most of its college students use to pay tuition, and sudden faculty closures strand college students mid-degree.
For debtors who’re behind, it’s a unique story. Collections resumed in Could 2025, wage garnishment is restarting, and the New York Fed has documented credit score rating drops averaging 91 factors for debtors who went from present to default.
A borrower already in default can get out via rehabilitation or consolidation, and the Division now runs an on-line portal for each.
The FY 2023 fee is being measured on deceptive information. The FY 2024 and FY 2025 charges would be the first actual take a look at of how the post-pandemic reimbursement system, together with the new RAP plan and the top of SAVE, is working.
Editor: Colin Graves
The publish The Official Pupil Mortgage Cohort Default Charge Is 0.4%. Right here’s Why That Quantity Means Nearly Nothing. appeared first on The School Investor.
Leave a Reply
Popular News
-

Path Act 2025 Tax Refund Dates
-
Banks Are Phasing Out Senior-Pleasant Checking Perks
-
Pupil Loans And Furloughs: What to Do Now
-
Free Owala Water Bottle at Dick’s Sporting Items after money again!
-
Tencent Music now has 20M+ ‘Tremendous VIP’ subscribers. Right here’s what which means for China’s largest music streamer.

