Properties at extreme threat outnumber federal flood insurance policies greater than three to at least one, and the hole is widest in poorer inland communities that FEMA’s maps miss
At this time second, with factoring in a predicted tremendous El Nini, roughly one in 12 US properties faces extreme or excessive flood threat. Fewer than one in 40 has a federal flood insurance coverage coverage.
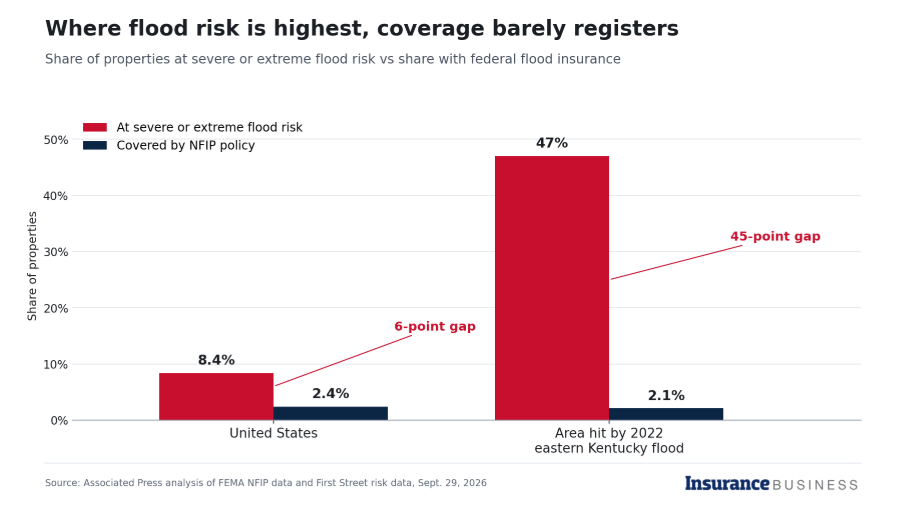
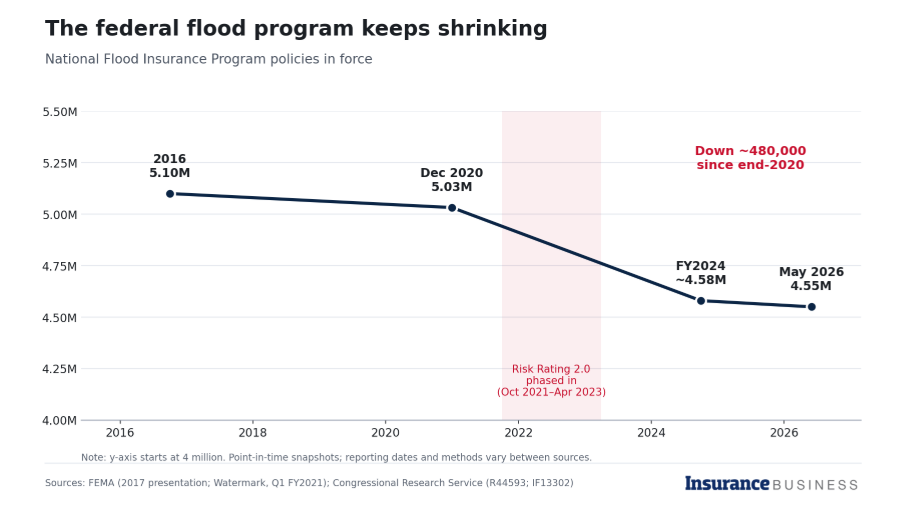
That mismatch comes from an Related Press evaluation printed yesterday. The examine mixed Nationwide Flood Insurance coverage Program information with property-level threat modeling from First Road. It counted roughly 4.5 million NFIP insurance policies, masking 2.4% of US properties, whereas 8.4% fall into the extreme or excessive threat tiers. That variety of insurance policies has been steadily falling, and has dropped by about half one million in 5 years.
For brokers and brokers, the findings verify what many already see with purchasers. The flood safety hole is widening at the same time as non-public capability grows and Washington talks about reform.
“Flood occasions have gotten extra frequent and extra widespread throughout america,” explains Carson Publish, nationwide underwriting director, flood at ICW Specialty. “And on the similar time, flood threat has turn out to be extra complicated, with each pluvial and fluvial flooding occurring extra usually. The severity of those occasions, together with the time required for communities and companies to recuperate, has additionally risen.”
Appalachia reveals how large the hole can get
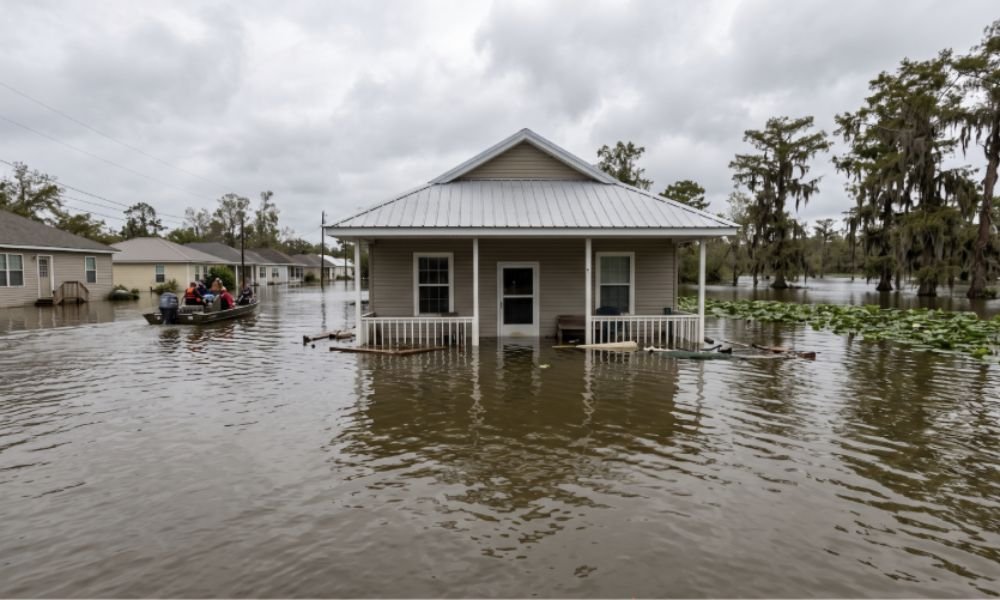
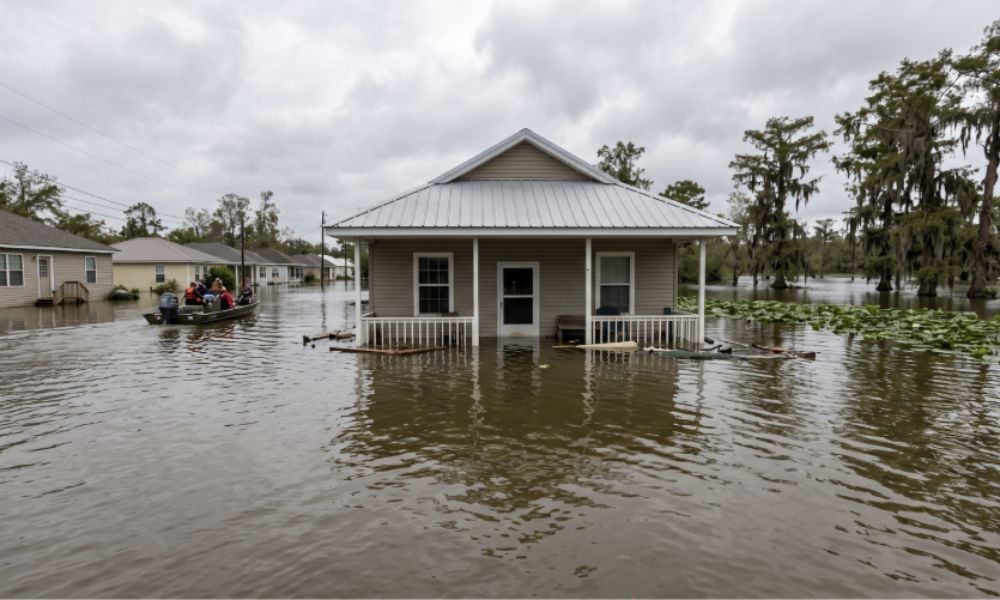
Nowhere is the hole starker than in japanese Kentucky. In July 2022, upwards of 12 inches of rain drenched the area, pouring off steep hillsides into tight hollows. The flooding killed greater than 40 individuals, and about 600 needed to be rescued by helicopter.
Within the space that flooded, solely roughly 2.1% of properties had flood insurance coverage, and the AP discovered that share has barely moved since. Practically half of properties there face extreme or excessive threat. That may be a 45-point unfold, greater than seven instances the nationwide hole.
Neptune Flood’s evaluation of the identical catastrophe discovered {that a} whopping 95% of broken houses had no flood insurance coverage. It additionally discovered that NFIP insurance policies in Kentucky, Tennessee and West Virginia actuallyfell 17% between 2021 and 2024.
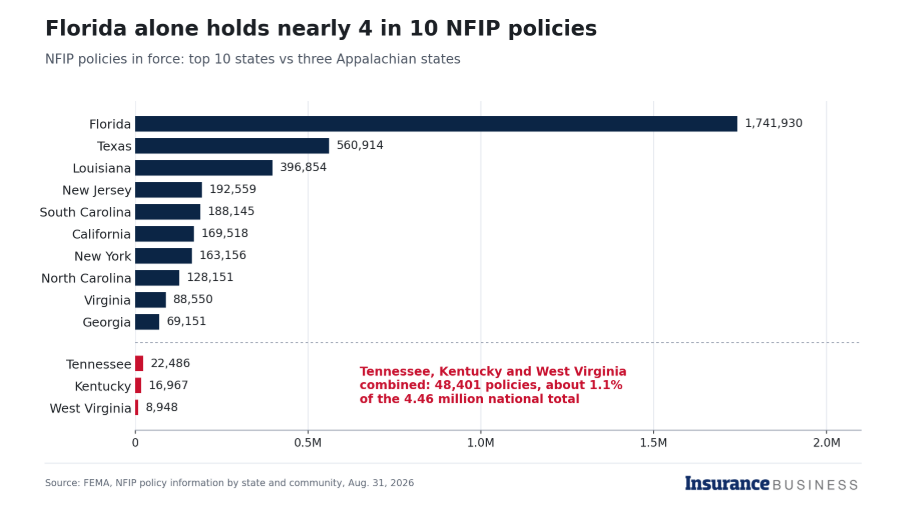
In apply, the NFIP is a coastal program. FEMA’s newest state-by-state coverage information, as of Aug. 31, reveals that Florida alone accounts for about 39% of this system’s 4.46 million insurance policies. Including Texas and Louisiana brings the highest three states to about 61%. Kentucky, Tennessee and West Virginia collectively maintain 48,401 insurance policies, about 1.1% of the entire.
Many Kentucky owners by no means knew they have been uncovered. Fewer than one in 5 buildings broken in 2022 have been in a FEMA-designated high-risk zone. Which means most homeowners have been by no means required to purchase protection, even these with federally backed mortgages.
“The largest mistake individuals make is assuming that if [their] enterprise isn’t in certainly one of FEMA’s high-hazard zones then [their] threat of flooding is minimal, and that [they], subsequently don’t have to buy any flood protection,” Publish advised Insurance coverage Enterprise. “Or, in the event that they do buy protection, they don’t purchase almost sufficient to guard their enterprise.”
Jeremy Porter, First Road’s chief economist, advised the AP that the most important protection gaps are the place heavy rain causes flooding removed from main rivers or coastlines. He named Appalachia, the Midwest and the Northeast. FEMA’s flood maps are sometimes outdated, and so they do not seize that sort of rain-driven inland flooding properly.
Personal carriers have been urgent the identical level. Neptune CEO Trevor Burgess advised Insurance coverage Enterprise in Could that “fashionable flood modelling identifies much more properties in danger than FEMA at present acknowledges.” Neptune’s analysis discovered that 45% of NFIP claims come from outdoors mapped floodplains.
Learn subsequent: Solely about 4% of US owners have flood insurance coverage – regardless of billions in annual losses
Correct pricing, unaffordable premiums
The opposite power pushing individuals out is worth, a typical NFIP coverage now prices about $1,100 a yr, up roughly 90% over 5 years.
A lot of that enhance comes from Threat Score 2.0, FEMA’s property-level pricing technique. It utilized to new insurance policies from October 2021 and to renewals from April 2022, and it was totally in place by April 2023. Its objective was to make every premium replicate the precise threat of the property.
Many underwriters would name {that a} sound precept, however for a big share of house owners it meant a lot larger payments. Federal auditors discovered that Gulf Coast insurance policies had been priced properly beneath their true threat earlier than the overhaul. Annual will increase for present insurance policies are capped at round 18%, so many policyholders are nonetheless working towards their full-risk price. The GAO doesn’t count on the phase-in to complete till 2037.
Researchers have measured how many individuals the will increase drove away. A peer-reviewed examine within the Journal of Disaster Threat and Resilience discovered that Threat Score 2.0 lower new NFIP insurance policies by 11% to 39% and present insurance policies by 5% to 13%. The larger a property’s premium enhance, the bigger the drop.
Prices are highest within the locations with the least protection. By FEMA’s August figures, West Virginia has the very best common annual NFIP value of any state, at about $2,280 per coverage together with charges and surcharges. Kentucky ranks sixth at about $1,825, and Tennessee ninth. Florida, which has by far probably the most insurance policies, averages about $1,177.
Sen. Invoice Cassidy, the Louisiana Republican, has criticized administrations of each events for retaining the brand new score system whereas his state’s owners soak up the value will increase.
When protection is in place, it may well determine how a household recovers. A family in Letcher, Kentucky escaped the 2022 flood and had an NFIP coverage. The declare paid off the remainder of their dwelling mortgage, so they may transfer to a close-by city freed from debt.
Washington buys time once more
This system was set to lapse at midnight on Sept. 30. As a substitute, Congress acted in early September, attaching an NFIP extension to a stopgap spending legislation that runs via Dec. 11. The Congressional Analysis Service counts it because the thirty sixth short-term reauthorization since fiscal 2017. The business remembers final fall, when a 43-day lapse froze new insurance policies and renewals and delayed dwelling closings.
Longer-term fixes are caught. Reform proposals have stalled, together with choices to make protection cheaper for lower-income households. “Everyone agrees it is damaged, however nobody can agree learn how to repair it,” Jeffrey Schlegelmilch, college director of Columbia College’s Nationwide Heart for Catastrophe Preparedness, advised the AP.
In Could, a White Home-ordered assessment concluded that the NFIP, which owes the Treasury greater than $20 billion, is flawed at its core. The FEMA Overview Council really helpful step by step transferring insurance policies to non-public insurers via a voluntary take-out program.
A CRS assessment of these suggestions famous a standard criticism in public feedback. The report stated nothing about premium charges, program funding, or learn how to get extra houses insured.
Some proposals in Congress would make it simpler for policyholders to maneuver between the NFIP and personal carriers. The bipartisan Steady Protection for Flood Insurance coverage Act would direct FEMA to deal with compliant non-public insurance policies as steady protection. Below present guidelines, a policyholder who switches to a personal provider can lose NFIP reductions in the event that they later return to this system.
FEMA says the reply lies in harder building requirements, higher land-use choices and a wholesome non-public market, not in Washington carrying the entire burden. The company says affordability is finally a query for lawmakers.
FEMA can be creating a alternative for at this time’s flood zones, an initiative generally known as Way forward for Flood Threat Information. It hasn’t stated when that shall be prepared.
Learn subsequent: Trump council approves FEMA overhaul, eyes non-public flood market
Personal capability shouldn’t be the bottleneck
The non-public market is rising however stays small. As of Could, non-public carriers wrote about 643,000 flood insurance policies, in contrast with about 4.55 million within the NFIP, based on CRS. Neptune estimates that greater than 15 million flood-exposed US properties haven’t any flood protection in any respect.
At Hiscox, flood specialists say capability is not the issue; the more durable activity is persuading clients to purchase. That’s very true the place incomes are low and nothing requires the acquisition. In japanese Kentucky, a nonprofit report discovered {that a} majority of households in flood-damaged houses had annual incomes beneath $30,000.
Learn subsequent: Personal flood capability is rising – so why aren’t extra clients shopping for?
What uninsured homeowners fall again on
Uninsured homeowners have little to fall again on. FEMA catastrophe assist is simply obtainable after a presidential declaration. Its two largest particular person help packages, one for housing and one for different wants, are every capped at a bit of over $40,000, adjusted yearly for inflation. Few candidates obtain the utmost.
Repeat disasters deliver one other catch. An proprietor in a flood zone who receives assist as soon as after which stays uninsured usually will not get assist the following time.
After the 2022 Kentucky floods, FEMA paid near $90 million in direct help. That was a couple of fifth of even the bottom estimate of rebuilding prices. Researchers on the Ohio River Valley Institute, together with senior researcher Eric Dixon, noticed a gradual exodus. Households moved in with family members, resettled elsewhere in japanese Kentucky, or left Appalachia altogether.