Key Factors
- A $5 match for each $1 saved: Sen. Jeff Merkley’s Homeownership Promise Act would give first-time homebuyers as much as $50,000 from HUD on high of $10,000 they save themselves, for as a lot as $60,000 at closing.
- Limits on who and what qualifies: Patrons have to be 18 or older, have by no means owned a house and end HUD-approved housing counseling. The house can’t price greater than the world’s median single-family worth, and the invoice units no earnings restrict.
- Nonetheless a protracted shot: The invoice has two Democratic sponsors and no greenback determine or price estimate. It wants Republican help to maneuver within the Senate earlier than the 119th Congress ends in January 2027.
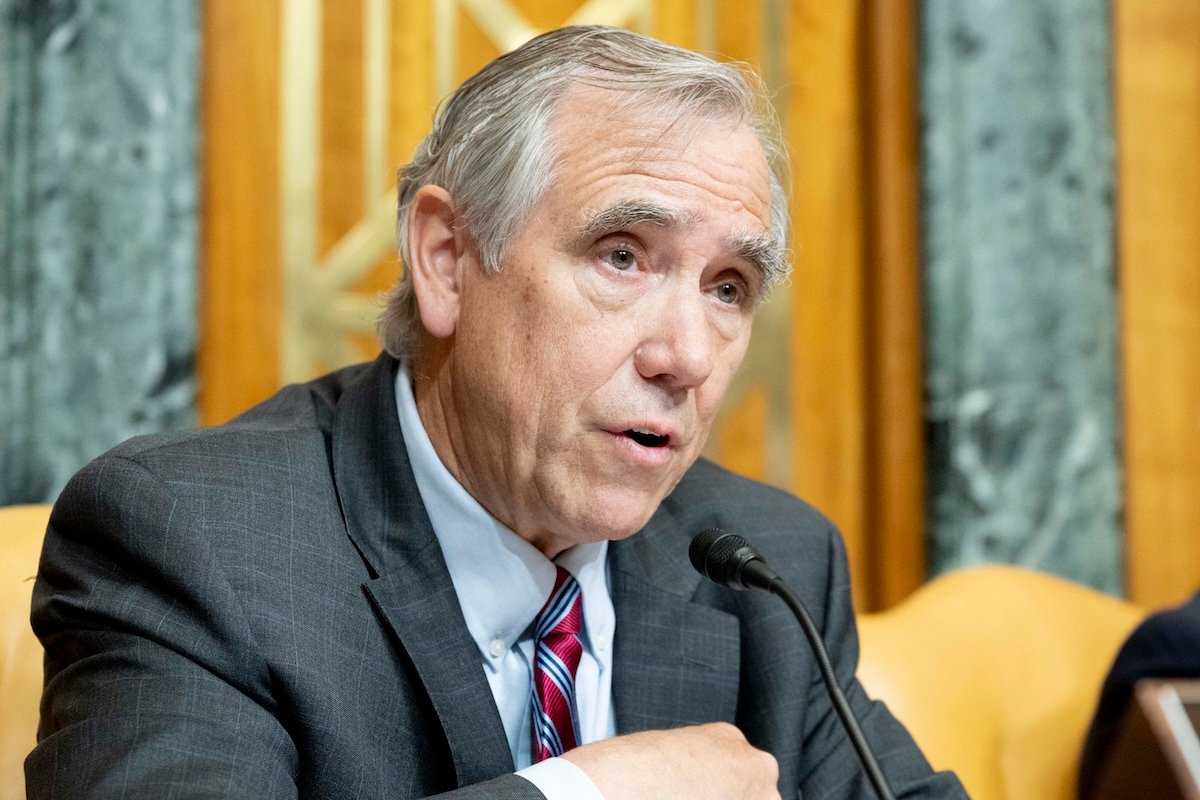
Sen. Jeff Merkley launched the Homeownership Promise Act (PDF File) on September 23, 2026, a invoice that may have the federal authorities match first-time homebuyers’ down cost financial savings at a 5-to-1 price. A saver who places away the $10,000 most would obtain as much as $50,000 from the Division of Housing and City Growth (HUD), for a mixed $60,000 at closing. Sen. Ron Wyden is the lone cosponsor, in keeping with Merkley’s announcement.
The brand new Homeownership Promise Accounts would operate as financial savings accounts with a big federal grant paid out on buy day. The idea resembles the match Lobby presents on house down cost financial savings and the $1,000 federal Saver’s Match coming to retirement accounts in 2027, however at a far bigger a number of.
The invoice defines an “eligible household” as one or two first-time patrons, so a pair shopping for collectively would share one account and one $60,000 cap reasonably than every opening their very own (one other marriage penalty).
Would you want to avoid wasting this?
Why It Issues
The everyday first-time purchaser is now 40 years outdated, the oldest on report, and first-time patrons accounted for simply 21% of purchases (a historic low) in keeping with the Nationwide Affiliation of Realtors’ 2025 Profile of House Patrons and Sellers. Merkley’s said aim is a reputable path to a modest house by age 30. Youthful patrons carrying pupil mortgage debt face a second squeeze, since pupil mortgage funds depend in opposition to your debt-to-income ratio when a lender figures out how a lot mortgage you’ll be able to qualify for.
The greenback quantities present why a 5-to-1 match is the fitting match. The median existing-home worth was $429,100 in August 2026, and NAR studies first-time patrons put down a median 10%, or about $42,900 at that worth. A maxed-out $60,000 account would cowl that with room to spare, equal to roughly 14% of the median house.
Constructing the identical steadiness alone in a high-yield financial savings account would take most younger households years longer.
The Particulars
Right here’s how the accounts would work:
- Eligibility: One or two first-time homebuyers age 18 or older who’ve by no means owned a principal residence and have accomplished a HUD-approved housing counseling program.
- House worth cap: The acquisition worth, excluding closing prices, can’t exceed the median single-family worth for the world as decided by HUD.
- Earnings limits: None seem within the invoice textual content (that is uncommon).
- The place accounts dwell: Any taking part Group Growth Monetary Establishment (CDFI), which should pay curiosity similar to its unrestricted financial savings accounts. Many CDFIs are credit score unions.
- Contribution caps: $10,000 mixed from private, employer, and nonprofit sources, plus as much as $50,000 in federal matching funds.
- What will get matched: The invoice ties the 5x grant to private contributions solely. Employer and nonprofit cash counts towards the $10,000 cap however, as written, doesn’t draw its personal match. A employee whose employer chips in $4,000 may personally save $6,000 and gather $30,000 in federal funds.
- Emergency entry: Savers can withdraw their very own contributions at any time, for any purpose, in any quantity. The abstract provides that matching grants would pay out solely after the total contribution steadiness is restored.
- Payout timing: HUD’s grant executes on the closing settlement, and as much as two eligible households can apply their accounts to the identical buy.
How This Connects
Congress has floated a number of first-time purchaser proposals this yr. A bipartisan Senate invoice launched in August would let savers pull as much as $35,000 tax-free from a 529 plan for a primary house, offered the account has been open at the least 15 years.
Present regulation already permits a $10,000 penalty-free IRA withdrawal for a primary house buy, although that possibility requires having retirement financial savings to faucet within the first place.
Merkley’s method stands aside as a result of it provides new federal {dollars} reasonably than unlocking tax breaks on cash households already saved, placing it nearer to the $1,000 Trump Account deposit for newborns than to a deduction.
Housing has been a long-running focus for Merkley, who ran Portland Habitat for Humanity earlier than coming into the Senate. His workplace credit him with the predatory mortgage ban within the 2010 Dodd-Frank Act and with the hedge fund single-family house buy ban within the twenty first Century ROAD to Housing Act, which just lately turned regulation.
What’s Subsequent
The invoice continues to be only a proposal. It solely has on cosigner and there’s no indication the Republican-controlled committee will even contemplate it. With out consideration, the proposal would expire when the 119th Congress ends in January 2027.
Till then, patrons can estimate how a lot home they’ll afford utilizing financial savings they management in the present day.
Editor: Colin Graves
The put up New Senate Invoice Would Give First-Time Homebuyers $5 For Each $1 They Save appeared first on The Faculty Investor.