Colorado’s highest court docket has dominated that when a major insurer goes broke, the surplus service above it would not have to select up the tab.
The Supreme Court docket of Colorado answered a licensed query from federal court docket on September 21, ruling unanimously that “not lined” in umbrella/extra insurance policies refers to protection scope – not whether or not the first insurer can really pay.
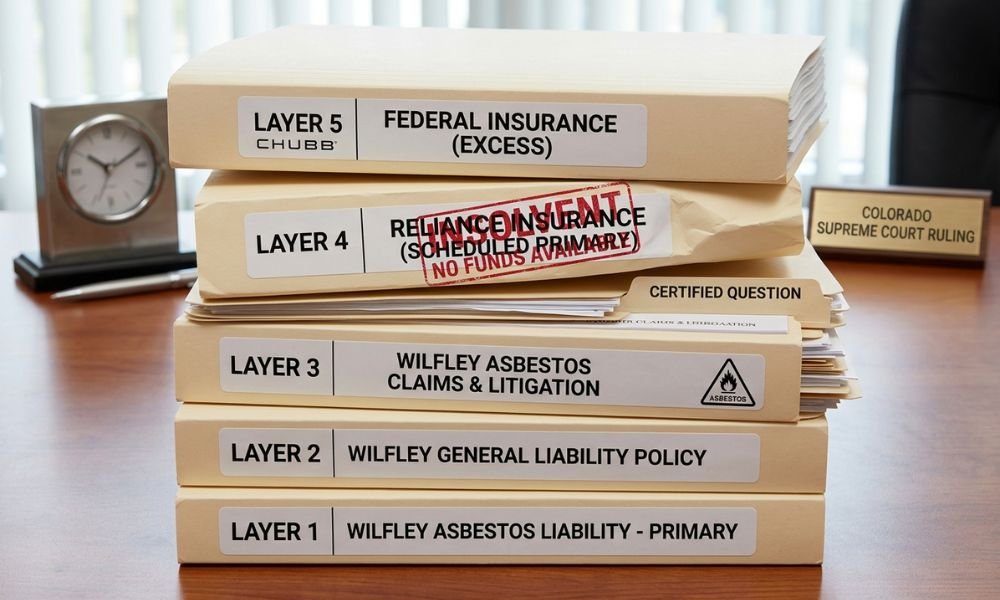
The case concerned A.R. Wilfley & Sons, a Colorado pump producer dealing with a long time of asbestos bodily-injury lawsuits. Wilfley’s insurance coverage was stacked in layers. On the base sat major insurance policies from Reliance Insurance coverage Firm. Above them, Federal Insurance coverage Firm – a part of the Chubb group – had issued umbrella/extra insurance policies.
When Reliance turned bancrupt, Wilfley misplaced entry to primary-layer funds, however the insurance policies themselves nonetheless technically lined the claims. Wilfley argued this meant the claims have been “not lined” below the Federal insurance policies – language that might pressure Federal to drop down and supply first-dollar protection and indemnity, which means it will pay from the primary greenback of loss.
Federal disagreed. “Not lined” meant the declare fell outdoors the underlying coverage’s scope, not that the insurer behind it was bancrupt.
The court docket agreed. It walked by means of three provisions within the Federal insurance policies, every utilizing “collectible” solely in reference to unscheduled insurers – carriers not listed within the coverage schedule. For scheduled insurers like Reliance, the insurance policies used “lined,” and lined meant inside scope. Treating the 2 phrases as interchangeable would make the collectibility language meaningless and convert Federal right into a monetary guarantor of each major insurer Wilfley had chosen – a danger it by no means priced and by no means accepted.
Wilfley had leaned on a 1989 Colorado Court docket of Appeals determination the place an extra service was held chargeable for protection prices after a major insurer turned bancrupt. The Supreme Court docket discovered that earlier ruling was grounded in fairness, not contract. Its temporary dialogue of the coverage language was pointless to the result – authorized reasoning that does not drive the outcome, referred to as obiter dictum, and never binding. The court docket overruled Deisch to the extent it conflicted.
The ruling aligns Colorado with federal appellate courts within the Fifth, Tenth, and Eleventh Circuits, plus a California appellate determination, all reaching the identical conclusion.