In 2012, two months earlier than my thirty fifth birthday, I engineered my layoff from a 13-year profession in funding banking. On the time, it felt just like the riskiest factor I had ever finished. Was I actually going to explode my profession proper as my incomes energy was about to compound?
It didn’t appear clever. And if I may do it over once more, I most likely would have labored 5 extra years till 40 to avoid wasting and make investments extra. To increase the drudgery, I might have pushed more durable to relocate to a different metropolis and switch the final stretch into an journey.
However now that I’m 14 years into FIRE and nearly 50, I’ve had a change of coronary heart. Retiring at 35 isn’t practically as dangerous because it feels within the second. Neither is the trail to get there as laborious because it sounds — saving and investing over 50% of your earnings for 13 years after faculty, or 17 years after highschool, is doable while you’re younger and have few obligations.
If issues do not work out after one to 3 years at age 35, you possibly can at all times return to work and discover one other soul-sucking job that makes you query your objective in life each single day. Seems grinding 60 hours every week is a surprisingly efficient spending deterrent.

Two Buddies Who Proved The Draw back Was Small
One good friend retired from banking at 33 to turn into a baker. She needed to get up at 6am and get yelled at by the pinnacle chef every day. She figured that if she was going to get yelled at both means, she may as effectively get yelled at in finance and make 8X extra. So she returned a number of years later, regardless of having a portfolio price about $2 million to dwell off.
One other good friend needed to be a photographer. She was at Fb making about $300,000 a 12 months, however she could not abdomen what the algorithm was doing to children’ brains. So she left and freelanced for a 12 months. The cash was horrible, however she had financial savings and went off to discover Cambodia, Taiwan, Vietnam. She truly saved cash whereas overseas as a result of the price of dwelling is a lot decrease.
After a 12 months, she realized she could not make it as knowledgeable photographer and went again to massive tech for the massive bucks. The cash was simply too good to disregard, regardless of having sufficient. Children be damned!
Each buddies had been of their early-30s. Each discovered work two years of taking their leap of religion to expertise FIRE and following their passions. Neither of them is on the road.
Retiring At 50 Is Brutally Arduous As a result of Of What You Have To Lose
I am within the final 12 months of my 40s, and I really feel melancholy that point glided by so rapidly. I might surrender nearly every part to rewind time by a decade.
If I had been nonetheless in finance as we speak, I would be strategizing proper now on easy methods to negotiate a severance and accumulate all my deferred compensation subsequent 12 months at 50.
However frankly, I do not know if I would have the ability to pull the set off based mostly on what’s in entrance of me.
With 15 extra years of labor expertise, I assume I would have made Managing Director by now. Meaning a base wage of round $500,000, plus a discretionary bonus someplace between $0 and $2 million for the typical MD.
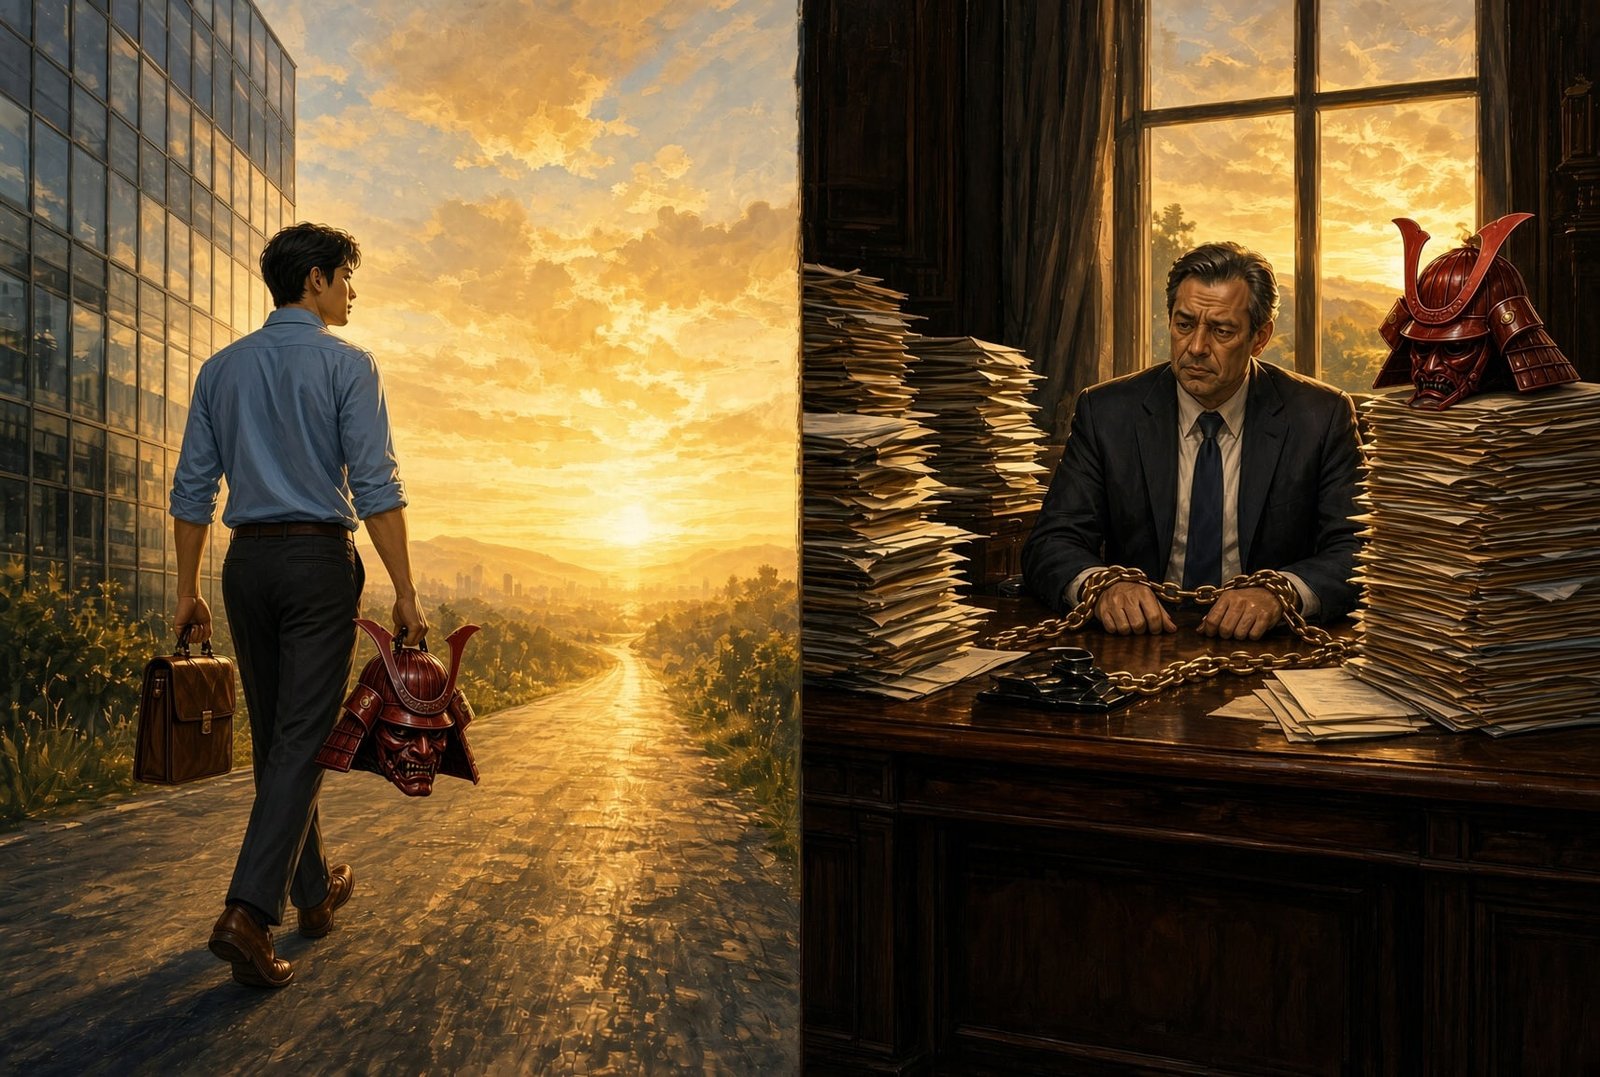
Strolling away from probably $2.5 million in whole compensation is way more durable than strolling away from $500,000, even after adjusting for inflation. The golden handcuffs do not loosen with time. They tighten.
Life-style Inflation Is The Actual Handcuff
If I had been making $1 million a 12 months on common for a decade, my way of life would have inflated to match. Larger home. Two children in personal college. A stay-at-home partner. Hiring gardeners, home cleaners, trainers, and possibly even cooks. As a result of why not? I’m bringing house the toro sashimi.
The stress to maintain offering for that life could be monumental as a result of there’s additionally college tuition arising and the need to create multi-generational wealth. Attempting to fund it with out a W-2 earnings and the potential of an enormous bonus would really feel nearly unattainable.
When individuals rely upon you, the intuition is to grind more durable, not much less.
That is partially why I am so fascinated by the rise of stay-at-home boyfriends and stay-at-home husbands who do not work in any respect. I might have thought the need to supply was baked into each man’s DNA. Guess not.
Rewind To 34, After I Had Virtually Nothing To Lose
Now let me rewind to after I was 34 and plotting my escape.
On the time, I had no youngsters and a working spouse. I wasn’t offering for her or for 2 little ones.
Each of my dad and mom had been wholesome, alive, and lately retired with authorities pensions. I felt zero stress about arising with $10,000 to $20,000 a month for elder care.
I used to be additionally solely two years into writing Monetary Samurai, which I felt had super upside. There have been no bloggers writing about finance who had truly labored in finance. All of them had been targeted on budgeting and saving as an alternative of pushing readers to earn and make investments extra.
It is nonetheless uncommon as we speak. The few finance individuals who do write about private finance are often nonetheless working at an RIA or a fund, utilizing the content material to draw clients. So it is probably not geared towards the FIRE group.
Most significantly, at 34 I knew I may get again into finance inside a 12 months or two if I wanted the cash. I additionally knew I may land some lower-level finance function at a tech startup if I actually needed to. The draw back threat of not discovering work was low.
At 50, The Job Market Does not Need You Again
At 49, it’s far more durable to discover a well-paying job on this economic system when you lose one.
AI has compressed the demand for information employees. And at 50, there are merely fewer roles obtainable at your stage of expertise and comp than there have been in your 20s and 30s.
So if I fired at 50, I might must be completely sure I used to be by no means coming again. The boats could be burned. No various however to dwell off investments and earn some facet hustle cash if wanted.
That certainty is a a lot heavier factor to hold at 50 than the informal “eh, I am going to determine it out” you get to say at 34.
Instance Of FIRE At 35 vs FIRE At 50
| Description | Retiring at 35 | Retiring at 50 |
|---|---|---|
| Comp you are strolling away from | ~$150,000 | ~$350,000 |
| Dependents | Normally none | Children, partner, getting older dad and mom |
| Capability to get rehired | Excessive, inside 12 months | Low, and at decrease pay |
| Life-style inflation | Minimal | Absolutely baked in |
| Years of bills to fund | 50+ | 35+ |
| Remorse if it fails | Misplaced a 12 months or three | Misplaced your final high-earning decade |
| Emotional issue | Feels terrifying, is manageable | Feels rational, is almost unattainable |
FIRE Will get Tougher As You Age, Not Simpler
Typical knowledge says that as you age and construct wealth, retiring early will get simpler. I am not positive that is true.
The older and wealthier you get, the extra you must lose.
You additionally accumulate obligations. In case you have a household, you carry extra concern to your youngsters than you ever did for your self. Given the economic system and the route AI is heading, you naturally begin excited about generational wealth so your children can be OK even within the worst-case situation.
Sadly, FIRE makes constructing generational wealth more durable, not simpler. Do you actually wish to be that egocentric to solely take into consideration your individual freedom when your youngsters will graduate college in an economic system that doesn’t welcome them?
Proper now, as a result of I’ve no sensible employment choices, the trail of least resistance is to remain retired. Ironic, however true.
Again in 2023, I did work part-time at a fintech startup for 4 months. It was a very good expertise that boosted my confidence that I may get employed once more if I actually needed to. However that clock is now expiring, as that was three years in the past.
That very same 4 months additionally jogged my memory precisely why I left within the first place. I am not constructed for conferences, commuting, and giving up my time for another person’s goals.
However I am going to admit it. After shopping for my home and dwelling paycheck to paycheck for six months, it felt actually good to have regular energetic earnings once more. If I would been making two to 5 occasions that quantity, leaving would have been means too laborious.
Being Trustworthy About Your FIRE Odds
The conclusion I’ve come to: if you wish to FIRE, do it younger (underneath 45). It is simpler to select your self up off the highway after getting hit while you’re younger and nonetheless have Wolverine-level regenerative powers. After 45, the restoration simply is not the identical.
Should you can, take a paid two or three month sabbatical to check the waters first. A one month sabbatical is solely not lengthy sufficient to provide you an actual style of what retirement is definitely like. Apart from, the primary month of a sabbatical is often paid, which may give you a false sense of safety.
If I had been sitting in a Managing Director seat as we speak with two younger children at house, there’s possibly a 20% likelihood I would muster the braveness to negotiate a severance and stroll.
The opposite 80%? I would inform myself to suck it up and grind no less than till my youngest graduated highschool in 2038. My daughter is six, in order that’s 12 extra years. I would be 61.
And being sincere with myself, I would most likely really feel stress to work 4 extra years to cowl faculty too. The costliest personal universities will value over $160,000 a 12 months in tuition alone by then. So name it 65.
That is not early retirement. That is simply retirement.
Therefore, the very best time to take the leap is the second it scares you most, not the second it lastly feels protected. As a result of in the event you watch for absolute certainty, you may by no means take that leap of religion.
Reader Questions
Do you assume it is more durable to retire early at 35 or at 50? Have your golden handcuffs gotten tighter as your earnings has grown?
For these of you who left a high-paying job in your 40s or 50s, what lastly pushed you over the sting? And for anybody who went again to work after retiring early, was the return simpler or more durable than you anticipated?
Lastly, in the event you’re a mum or dad, has having youngsters made you extra prone to maintain grinding or extra decided to get out?
Negotiate an Exit
Should you’re excited about leaving a job you not need, do not give up. Get laid off as an alternative. Negotiating a severance is what gave me the monetary runway and the peace of thoughts to stroll away in 2012 with deferred compensation plus a six-figure test. Choose up a replica of How To Engineer Your Layoff to discover ways to negotiate a severance your self. Use code “saveten” to avoid wasting $10 at checkout.

Subscribe to The Monetary Samurai E-newsletter
If a good friend forwarded you this put up, be a part of 60,000+ readers and subscribe to the free Monetary Samurai e-newsletter at https://www.financialsamurai.com/information. You may also join at https://www.financialsamurai.com/e mail to get new posts the second they publish, ad-free for the primary few hours.
Every thing I write is predicated on firsthand expertise since 2009, as a result of cash is simply too necessary to be left as much as pontification.