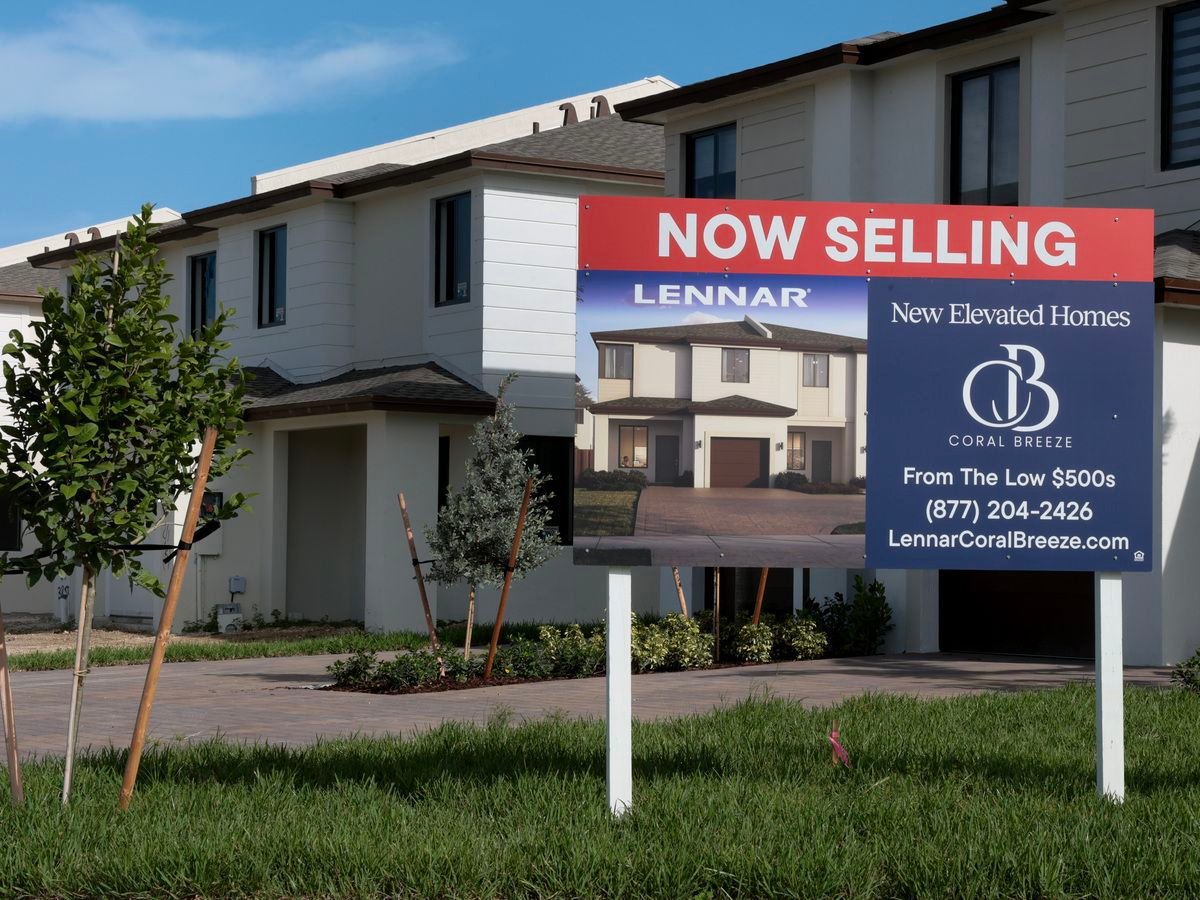
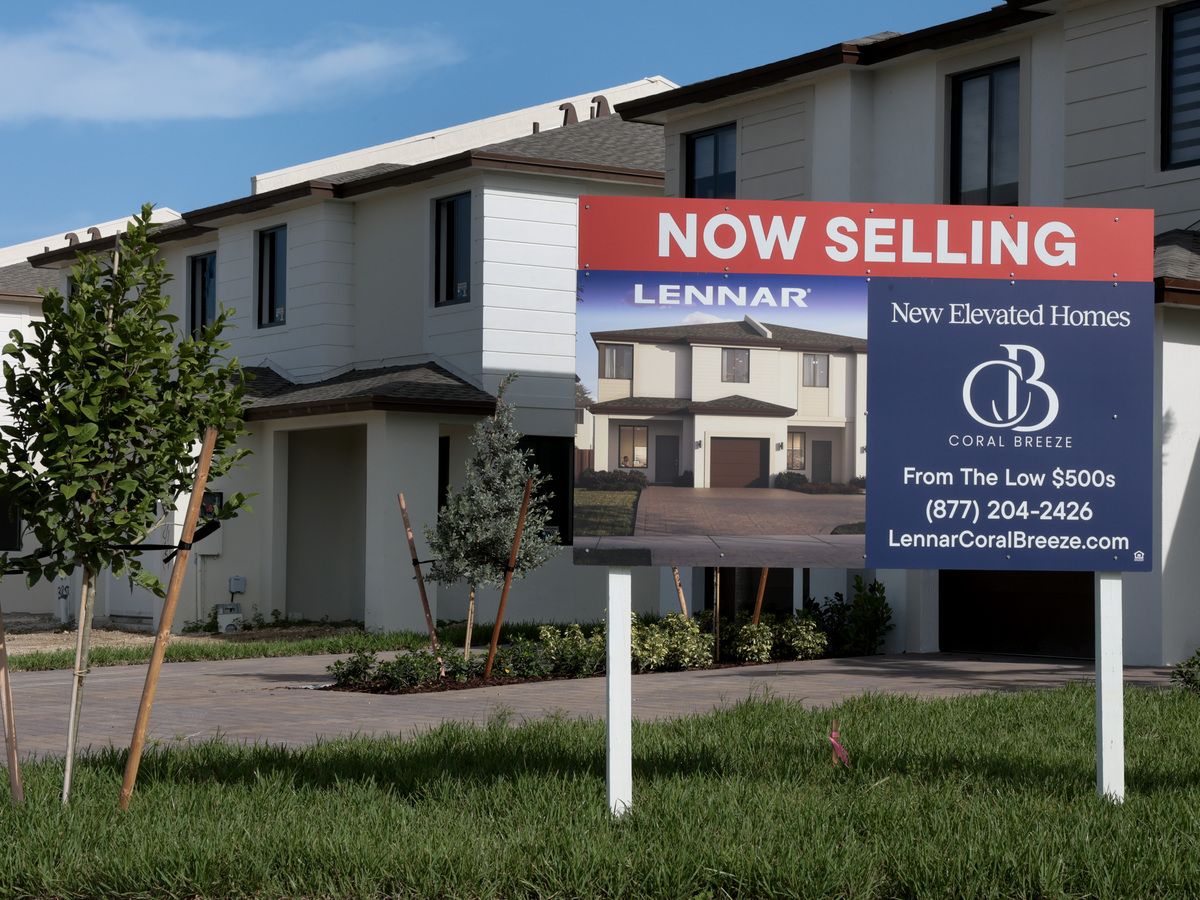
Canadians renewing their mortgages this yr would possibly want they have been a part of the American system that locks charges in for 30 years. However because the saying goes, watch out what you would like for.
About 60 per cent of Canadians with mortgages have been anticipated to resume in 2025 and 2026, about one third of them at greater charges .
5-year mortgage charges that fell beneath 1.5 per cent a half decade in the past have been the deal of a lifetime, and never surprisingly, Canadians took benefit.
In the meantime, Individuals who locked into mortgages on the backside of the market proceed to get pleasure from charges that dipped beneath three per cent for a 30-year mounted mortgage , based on the Federal Reserve Financial institution of St. Louis. Right now, the typical 30-year mortgage within the U.S. is 6.95 per cent.
The hidden draw back south of the border is the “lock-in impact,” by which few shoppers are keen to promote their properties as a result of they can’t port their super-low mortgage charges to a different property , based on a former U.S. federal housing commissioner.
“The housing market is a bit of stalled proper now,” mentioned Frank Cassidy, now a senior director of Walker & Dunlop, one of many largest business actual property finance and advisory companies corporations in america.
He mentioned Individuals traditionally financed mortgages that approach as a result of the federal government backed the loans and shoppers wished the protection of the speed maintain.
It’s necessary to do not forget that whereas Canadians could amortize their loans over 25 and even 30 years, making funds palatable as a result of they’re unfold out as if you’ll maintain the debt that lengthy, the preferred mortgage time period is often 5 years, which finally leaves you depending on the financial institution renewing your mortgage.
Mortgage renewals have largely been a given in Canada for many years, even when charges change, as we’re seeing at present. But when your own home has dropped in worth and and is now value lower than the quantity remaining in your mortgage, these renewals could not be so automated.
It’s not that Individuals don’t pay a worth for this fee safety: the 30-year mortgage can simply be one share level greater than the Canadian five-year mortgage. And with the mortgage being tied to the property, the price of shifting can turn into punishing.
“Lots of people will simply maintain their property and hire it,” mentioned Cassidy, about what occurs if you wish to transfer for one thing like a job. “I’ve a number of rental properties and mortgages between two and three per cent, and that’s why I’ve stored them.”
Cassidy mentioned that though American householders can not port their mortgage to a brand new property, they will promote their house with the prevailing mortgage and fee. The issue is that rising house costs over time imply any purchaser would wish a second mortgage or extra fairness to cowl the hole, complicating any sale.
Cassidy mentioned he thinks the reply within the U.S. is to “unclog” the market by specializing in supply-side initiatives, one thing that would cut back costs.
Earlier than we get boastful about Canadian housing coverage, let’s keep in mind gross sales aren’t exploding right here both. Throughout the nation, August gross sales have been down 6.9 per cent from a yr in the past, based on the Canadian Actual Property Affiliation. New house development is down virtually 5 per cent from a yr in the past for the primary eight months of the yr, based on Canada Mortgage and Housing Corp.
Jason Mercer, chief economist with the Toronto Regional Actual Property Board, doesn’t endorse both system however says each have simply developed in their very own approach over a long time, and now it’s simply conference.
“A few of that is linked again to how the mortgages are funded,” mentioned Mercer, including that the sale of five-year bonds is extra frequent right here.
He additionally identified different components that transfer the markets, similar to interest-rate deductibility in america and the absence of capital positive factors tax on the sale of a principal residence in Canada.
Canadians even have proven virtually no urge for food for longer fixed-term mortgages, with low demand for 10-year fixed-rate mortgages, which may simply be a share level greater than five-year phrases.
“You possibly can’t have each. You possibly can’t have flexibility and fee certainty, and so they form of battle,” mentioned Stillman, noting Individuals can not refinance properties with out dropping the exiting fee, one thing nobody needs to do when charges are rising.
“When charges have been at two or three per cent (in america), it was an incredible factor. All people (in Canada) ought to have taken a 10-year mortgage at 2.5 per cent.”
However he was additionally writing five-year mortgages as little as 1.35 per cent on the backside of the market.
“No one ever did it as a result of everyone was super-focused on how a lot home I should buy and what’s my lowest cost. We acquired suckered into it and informed charges would keep low for a very long time,” mentioned Stillman, pointing fingers at former prime minister Justin Trudeau and the Financial institution of Canada for sending out that message.
Ron Butler, a mortgage dealer, mentioned decrease home costs in america can spur house possession despite greater charges, but in addition famous Individuals can bounce right into a mortgage figuring out they will stroll away from their mortgage.
“You simply hand the keys to the financial institution, and so they can not chase you,” he mentioned, one thing not the case within the crumbling Canadian condominium market. “Why are all these individuals who purchased pre-construction condos who misplaced 40 per cent closing? They know the builder will chase me. They’ll power me into chapter 11.”
Butler mentioned the share of 10-year mortgages is lower than one per cent, and he chalks that as much as most Canadians dwelling by means of a relentless housing growth with a number of exceptions.
The U.S. system offers stability when charges are low, however it limits market development since you are caught, particularly if costs go down, mentioned Stillman.
“It simply limits selection, limits freedom,” mentioned Stillman. “What time period is … lengthy sufficient that it provides you stability, however it’s quick sufficient that you just don’t really feel handcuffed?”
• E-mail: gmarr@postmedia.com