Brokers have purpose to be extra cautious
California’s insurance coverage commissioner race has simply picked up an unlikely new voice: a libertarian-leaning suppose tank that wishes voters to know the state’s regulatory reforms are working, and that the fallacious winner in November might undo them.
The Pacific Analysis Institute, a San Francisco-based suppose tank that describes its mission as advancing free-market options, launched a brand new report this week titled “How California Burned Down Its Residence Insurance coverage Market and Why Regulatory Reform Can Rebuild It.”
Written by Free Cities Middle director Steven Greenhut, the booklet argues that Proposition 103’s rate-approval system, not wildfire danger itself, turned California’s house insurance coverage market right into a disaster. It warns that the state’s subsequent insurance coverage commissioner might reverse the progress made underneath outgoing commissioner Ricardo Lara.
For brokers who spend their days attempting to put protection within the state’s highest-risk ZIP codes, the argument will sound acquainted. A lot of it echoes what carriers and their commerce teams have mentioned for years about Proposition 103, the 1988 poll initiative that provides California’s Division of Insurance coverage authority to approve or reject charge adjustments.
What’s new is the timing: the report lands simply as voters put together to decide on between two Democrats, state senator Ben Allen and former San Francisco supervisor Jane Kim, whose approaches to the FAIR Plan and charge regulation diverge sharply.
Learn subsequent: What California’s insurance coverage commissioner race means for brokers within the nation’s hardest market
The case the booklet makes
Greenhut’s argument runs roughly like this: California’s wildfire danger is actual, nevertheless it is not what emptied the state’s insurance coverage market. As an alternative, he factors to Proposition 103’s charge approval course of, which for years barred insurers from pricing in reinsurance prices or utilizing forward-looking disaster fashions, forcing them to set charges utilizing historic loss knowledge alone.
As wildfire losses mounted and insurers could not get charge will increase authorized quick sufficient to maintain up, a number of giant carriers, together with State Farm and Allstate, stopped writing or renewing householders insurance policies in high-risk components of the state.
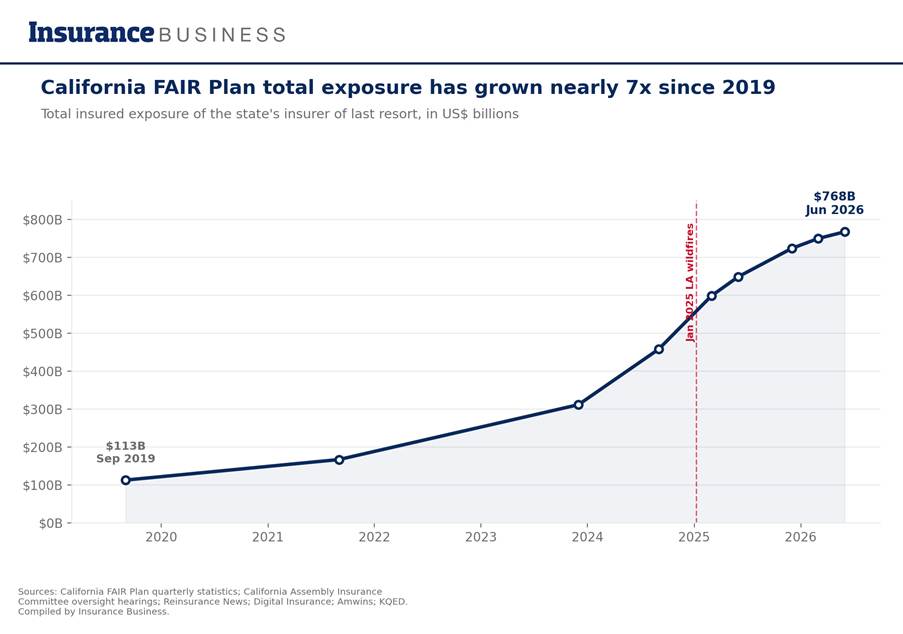
The outcome was that tons of of hundreds of householders have been pushed onto the California FAIR Plan, the state’s insurer of final resort. In response to figures compiled by wholesale dealer Amwins and cited within the booklet, the FAIR Plan’s complete publicity reached roughly $750 billion by March 2026, up 242% since September 2022. More moderen knowledge reported by KQED places the FAIR Plan’s publicity even larger, at $768 billion as of June 2026, in opposition to a direct money steadiness of solely $200 million to $400 million.
The booklet credit Lara’s Sustainable Insurance coverage Technique with starting to show issues round. The technique sped up charge critiques, allowed insurers to make use of disaster modeling, and allow them to issue reinsurance prices into filings.
The report cites a number of carriers saying plans to develop underwriting within the state as proof the reforms are working, and warns {that a} coverage reversal underneath the fallacious commissioner might ship these carriers “heading for the exits once more.”
Learn subsequent: Allstate strikes to reopen California house insurance coverage marketplace for first time in 4 years
The place the image will get extra difficult
A number of issues separate the booklet from a simple market evaluation.
First, the supply. The Pacific Analysis Institute is a free-market advocacy group, not a impartial analysis physique. It has described its personal mission as championing “particular person freedom and private duty” by way of limited-government coverage, and impartial bias trackers comparable to Media Bias/Truth Test place it on the best of the spectrum with a constant choice for deregulation. That does not make its information fallacious, however the framing is constructed to help a predetermined conclusion: that charge regulation, not underwriting self-discipline or local weather publicity, is the first villain.
Second, the reforms it praises have not absolutely solved the supply downside the booklet is celebrating. Even because the report notes development in FAIR Plan insurance policies is slowing, precise enrollment stored climbing by way of most of 2025 and into 2026, and the plan’s publicity has continued to rise, not fall, because the reforms took impact.
Within the highest-risk ZIP codes, roughly 41% of properties are actually coated by the FAIR Plan, in contrast with simply 4% in lower-risk areas. That is hardly a market functioning usually. And regulators authorized a 29.1% common charge improve on FAIR Plan dwelling insurance policies, efficient October 15, which can hit wildfire-exposed shoppers far more durable than the statewide common suggests.
Learn subsequent: FAIR Plan charge hike provides to California householders insurance coverage pressure
Third, the booklet’s characterization of the political backdrop is a little bit tidier than actuality. It frames the talk as one the place Sacramento “spent weeks combating over who ought to pay for wildfire losses” following the collapse of Governor Gavin Newsom’s wildfire legal responsibility push.
That is broadly correct. A final-minute deal between Newsom and legislative leaders to restrict utility legal responsibility for wildfires sparked by their tools did collapse on the finish of the legislative session, after PG&E and Southern California Edison argued it did not go far sufficient.
However the battle wasn’t merely pro-regulation versus pro-market. Insurers themselves, together with hearth survivors and trial attorneys, lobbied in opposition to provisions that may have barred them from pursuing subrogation claims in opposition to utilities, a mechanism carriers depend on to get better claims payouts and, in idea, hold charges decrease.
That is a element brokers advising business and private strains shoppers with utility-adjacent publicity will wish to watch carefully as the problem resurfaces underneath the following governor.
What it means for the November race, and for brokers
The commissioner race itself is the place the booklet’s stakes turn out to be concrete. Allen has pledged to construct on Lara’s reforms, favoring continued private-market growth, extra Division of Insurance coverage employees to deal with claims complaints, and tighter FAIR Plan accountability.
Kim has proposed a publicly run “Catastrophe Insurance coverage for All” program, funded by premiums paid right into a state authority, that may assure wildfire and flood protection outdoors the standard market.
For brokers, a continuation of the present reform path doubtless means extra admitted capability slowly returning to distressed ZIP codes, alongside continued reliance on E&S markets within the meantime. A state-run catastrophe fund, against this, would introduce a wholly new distribution channel and potential competitor for each admitted carriers and surplus strains markets on the hardest-to-place accounts.
Brokers would wish to rethink placement technique for wildfire-exposed shoppers virtually in a single day.
Learn subsequent: Who will repair California’s insurance coverage disaster? Main outcomes level to 3
Whichever candidate wins in November, most brokers lively within the state would in all probability agree on one level no matter their politics: the market has stopped shrinking, nevertheless it hasn’t but returned to one thing that features usually for householders within the highest-risk zones.
Whether or not the credit score for that stabilization belongs to deregulation, to Lara’s particular mixture of reforms, or just to a few quieter wildfire seasons is strictly the argument that may play out on Californians’ ballots this fall.