Bipartisan invoice launched this week would bar federal regulators from punishing insurers, brokers and brokers
For an trade that has spent the higher a part of a decade watching hashish insurance coverage keep caught in a authorized grey zone, this week introduced a well-known form of déjà vu.
On September 16, Representatives Nydia Velázquez (D-NY) and Warren Davidson (R-OH) reintroduced the Clarifying Legislation Round Insurance coverage of Marijuana (CLAIM) Act within the Home, a invoice designed to cease federal companies from going after insurers, brokers and brokers just because they select to write down enterprise for state-licensed hashish operators.
It’s the fourth consecutive Congress during which some model of this measure has surfaced, relationship again to a 2019 invoice Velázquez filed with then-Consultant Steve Stivers.
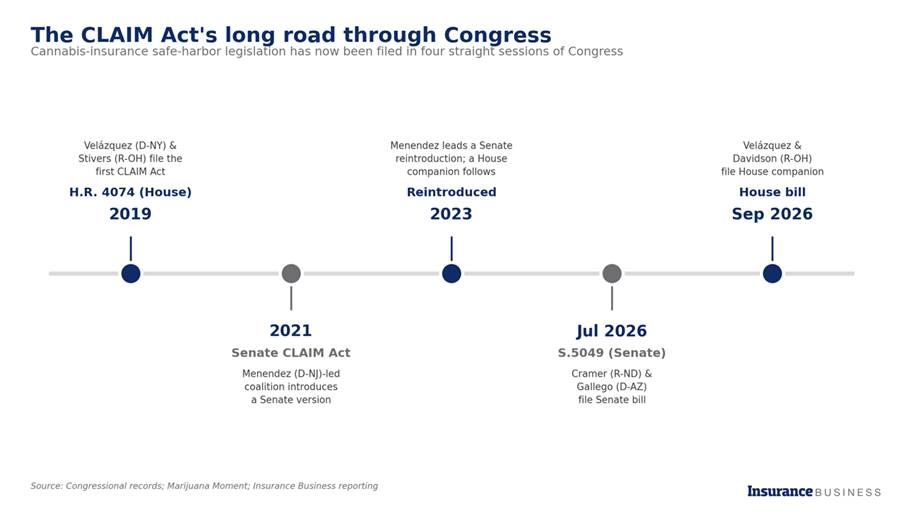
What’s totally different this time is timing. A companion invoice, S.5049, was already filed within the Senate in July by Senators Kevin Cramer (R-ND) and Ruben Gallego (D-AZ) and referred to the Banking, Housing and City Affairs Committee, which means the Home sponsors aren’t ranging from zero, they’re making an attempt to construct momentum round a measure that is already transferring by means of the higher chamber.
Learn subsequent: Senate invoice would defend insurers overlaying authorized hashish
What the invoice would truly change
Strip away the politics and the CLAIM Act is a reasonably slim piece of drafting. It could forestall federal companies from prohibiting, penalizing or “in any other case discouraging” an insurer from doing enterprise with a “cannabis-related legit enterprise,” or with a state, tribe or native authorities that regulates one. It could additionally cease regulators from leaning on insurers to cancel, downgrade or in any other case restrict protection purely as a result of a policyholder touches the hashish provide chain cultivating, manufacturing, transporting, dishing out or promoting it.
Notably, the invoice would not drive anybody’s hand. No insurer can be required to write down hashish threat below the CLAIM Act; it merely removes the federal publicity for those who already need to. It additionally leaves the McCarran-Ferguson Act and Dodd-Frank untouched, a element price flagging for compliance groups, because it means state insurance coverage regulators slightly than Washington would stay firmly answerable for how these insurance policies are literally priced and bought, as Insurance coverage Enterprise reported when the Senate model dropped.
Tucked into the invoice can also be a directive for the Authorities Accountability Workplace to review the particular boundaries reminiscent of licensing hurdles, entry to capital and insurance coverage entry that girls and minority entrepreneurs face making an attempt to interrupt into the hashish trade, then report the findings again to Congress.
Why insurers are watching now, not simply cheering
Velázquez framed the invoice that with out protection, a single hearth or storm can wipe out a hashish operator that has no solution to recuperate. Davidson’s pitch leaned extra on federalism, that Washington should not be second-guessing which lawful companies a state has chosen to license.
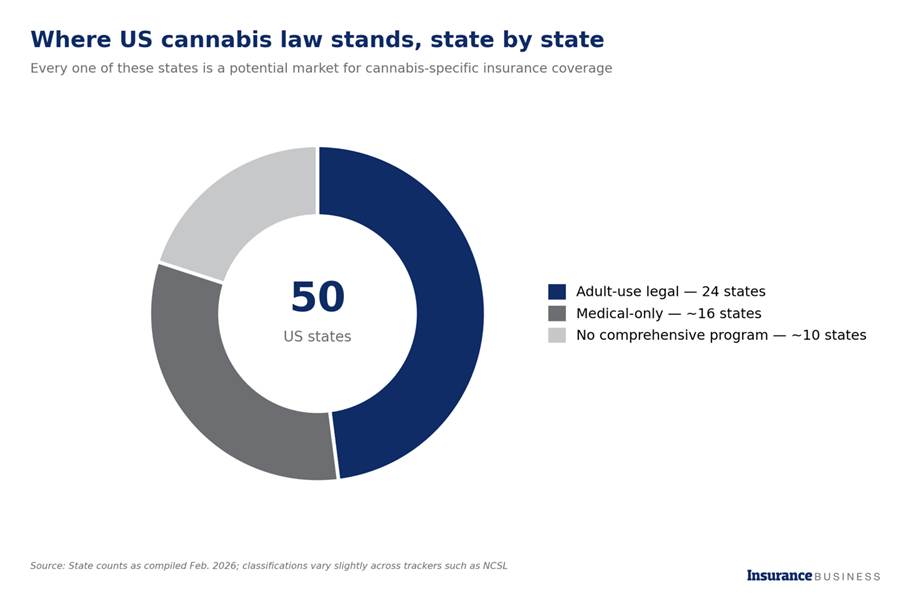
However the extra attention-grabbing viewers for this invoice is not state legislatures, it is the carriers, MGAs and wholesalers who’ve spent years pricing hashish threat in a market nonetheless dominated by surplus traces gamers. Beneath present federal regulation, hashish is classed as Schedule I for grownup use and Schedule III for medical use which suggests two totally different federal buckets, each nonetheless in need of full legality.
That is precisely the form of break up classification that makes broad, admitted-market underwriting uncomfortable. Many giant carriers have merely averted the house, cautious that complete hashish protection might expose them to federal money-laundering or racketeering theories regardless of the rescheduling exercise insurers have been watching intently.
That hesitation has a real-world price ticket, however it could already be easing. Mike McGee, a vice chairman at Arizona-based Crest Insurance coverage who works with hashish operators, informed Phoenix public radio station KJZZ that he is “operating into fewer and fewer hashish companies that do not have insurance coverage” already, and that passage of the CLAIM Act would doubtless draw extra carriers into the house.
“Increasingly carriers are going to be prepared to supply protection,” he mentioned. “And that breeds competitors. And that ultimately will begin to make insurance coverage premiums go down, not up.” Individually, a 2026 evaluation from personal-finance web site MoneyGeek put typical dispensary insurance coverage prices at roughly 35% above the broader retail common – a spot that displays skinny capability greater than claims historical past, based on brokers within the house.
Learn subsequent: Aon-owned NFP expands into hashish insurance coverage with Frontier Threat deal
The commerce teams lining up behind it
A coalition of 9 nationwide associations spanning property-casualty, life, title and reinsurance pursuits, together with the American Property Casualty Insurance coverage Affiliation, the American Council of Life Insurers, the American Land Title Affiliation, the Reinsurance Affiliation of America and the Wholesale & Specialty Insurance coverage Affiliation wrote to the invoice’s sponsors on September 8 backing the measure, arguing the trade stays uncovered to legal responsibility created by the mismatch between state and federal hashish regulation.
That is a notably broad coalition for a distinct segment line of enterprise, and it suggests the trade views the present authorized ambiguity as a real legal responsibility downside for carriers and distributors, not only a missed development alternative.
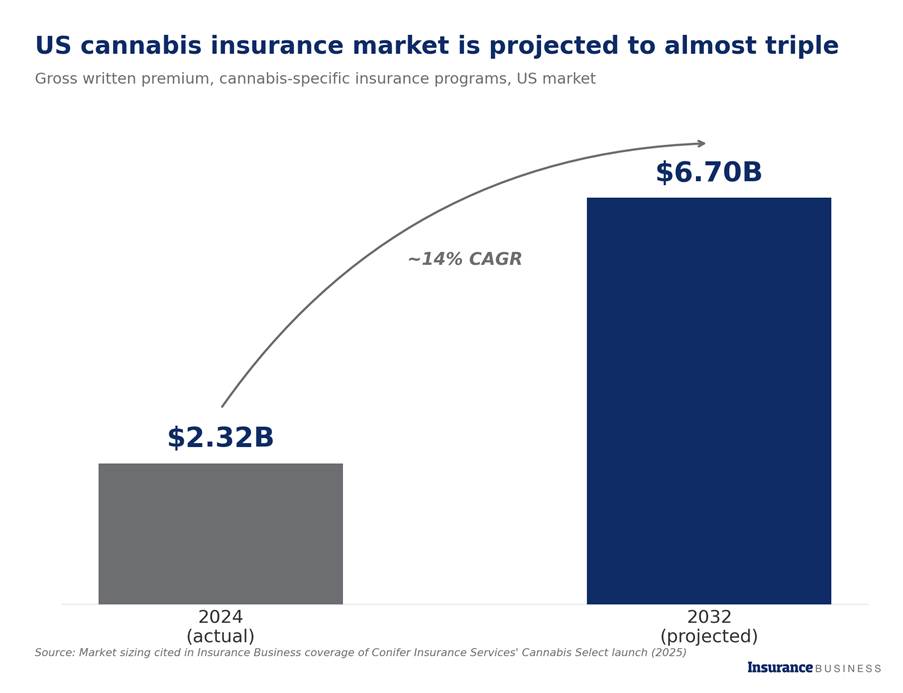
And the expansion alternative is actual, even when it has been slower to materialize than some anticipated. The hashish insurance coverage section was valued at roughly $2.32 billion in 2024 and is projected to climb to about $6.7 billion by 2032, a compound annual development charge of roughly 14%, based on market sizing cited in Insurance coverage Enterprise’s protection of Conifer’s Hashish Choose program launch. Whether or not that development accelerates doubtless relies upon much less on advertising and marketing and extra on precisely the form of federal legal responsibility defend the CLAIM Act is proposing.
Learn subsequent: Navigating highs and hazards within the hashish insurance coverage market
Is it going to cross?
This is the catch price flagging to purchasers and colleagues who would possibly see headlines and assume the issue is already solved: this invoice has didn’t cross in three earlier Congresses.
There’s nothing on this reintroduction that ensures a special end result, and the Senate companion continues to be sitting in committee with no flooring vote scheduled. For brokers and brokers advising hashish purchasers right now, the sensible steering hasn’t modified as protection nonetheless must be sourced primarily by means of surplus traces markets and specialty MGAs constructed for the house, not assumed to be newly accessible by means of normal admitted carriers.
What has modified is the broader path of journey. Between the rescheduling course of working by means of federal companies, a parallel push on the banking aspect by means of the SAFE Banking Act, and now insurance-specific laws advancing in each chambers with unusually broad trade-group help, the items of a extra normalized hashish financial-services market are, at minimal, being assembled in parallel even when none of them has crossed the end line but.
The Home invoice has been referred to committee. No listening to date has been set.